Best Payroll Software for Cannabis-Industry Businesses in 2026
Best Payroll Software for Cannabis-Industry Businesses in 2026 | StrategyDriven Managing Your Finances Article

Running payroll in the cannabis space is genuinely one of the more punishing administrative tasks any business owner faces. Payroll Software for Cannabis-Industry businesses has to account for IRS Section 280E, which strips out standard deductions and inflates your taxable payroll burden in ways that catch people off guard. Add limited banking access, constantly shifting state labor laws, and multi-jurisdiction tax codes, and you’re dealing with a compliance puzzle most general payroll tools weren’t designed to solve. After reviewing the leading platforms across the cannabis payroll software space, this guide breaks down exactly which options hold up under real operational pressure.

How the Picks Were Chosen

Each platform was assessed using publicly available information drawn from official product pages, user review platforms, software directories, and case study documentation. Only providers with a demonstrated track record in cannabis payroll software made the final cut.

→ See the full research breakdown

  • Hybrid Payroll – Best for cannabis industry payroll and compliance
  • BambooHR – Best for small to medium-sized business HR and payroll management
  • Rippling – Best for enterprise employee management and payroll automation
  • Paychex – Best for small to medium-sized business payroll and HR outsourcing
  • Gusto – Best for small to midmarket business payroll and HR management

Why Payroll Software for the Cannabis Industry Is Worth the Investment

Choosing the wrong payroll tool in this industry doesn’t just slow you down. It creates real financial exposure.

IRS Section 280E means cannabis businesses can’t deduct ordinary payroll-related expenses the way other industries do, so payroll tax obligations run heavier than most operators expect. On top of that, limited banking access turns routine payroll tax deposits into genuine logistical challenges that need careful planning.

Specialized payroll software built with cannabis operations in mind handles these pressure points differently than a generic platform would. The right tool works cleanly across multiple jurisdictions, keeps your 280E compliance cost impact from spiraling, and cuts down on payroll errors so each pay period runs on time.

The payoff shows up in faster time-to-process payroll, cleaner tax filing accuracy across every state you operate in, and fewer correction cycles eating into your HR team’s time.

Payroll Software For Cannabis-Industry: Comparison Table

Note: All data in this table is sourced from review platforms and the official websites of the listed companies.

Company Name Years Operating Team Size Headquartered In
Hybrid Payroll Est. 2014 51-200 employees Denver, Colorado
BambooHR Est. 2008 1,627 employees Draper, Utah
Rippling Est. 2016 7,131 employees San Francisco, CA
Paychex Est. 1971 ~19,000 employees Rochester, New York
Gusto Est. 2012 4,008 employees San Francisco, CA

Hybrid Payroll – Best for Cannabis Industry Payroll and Compliance
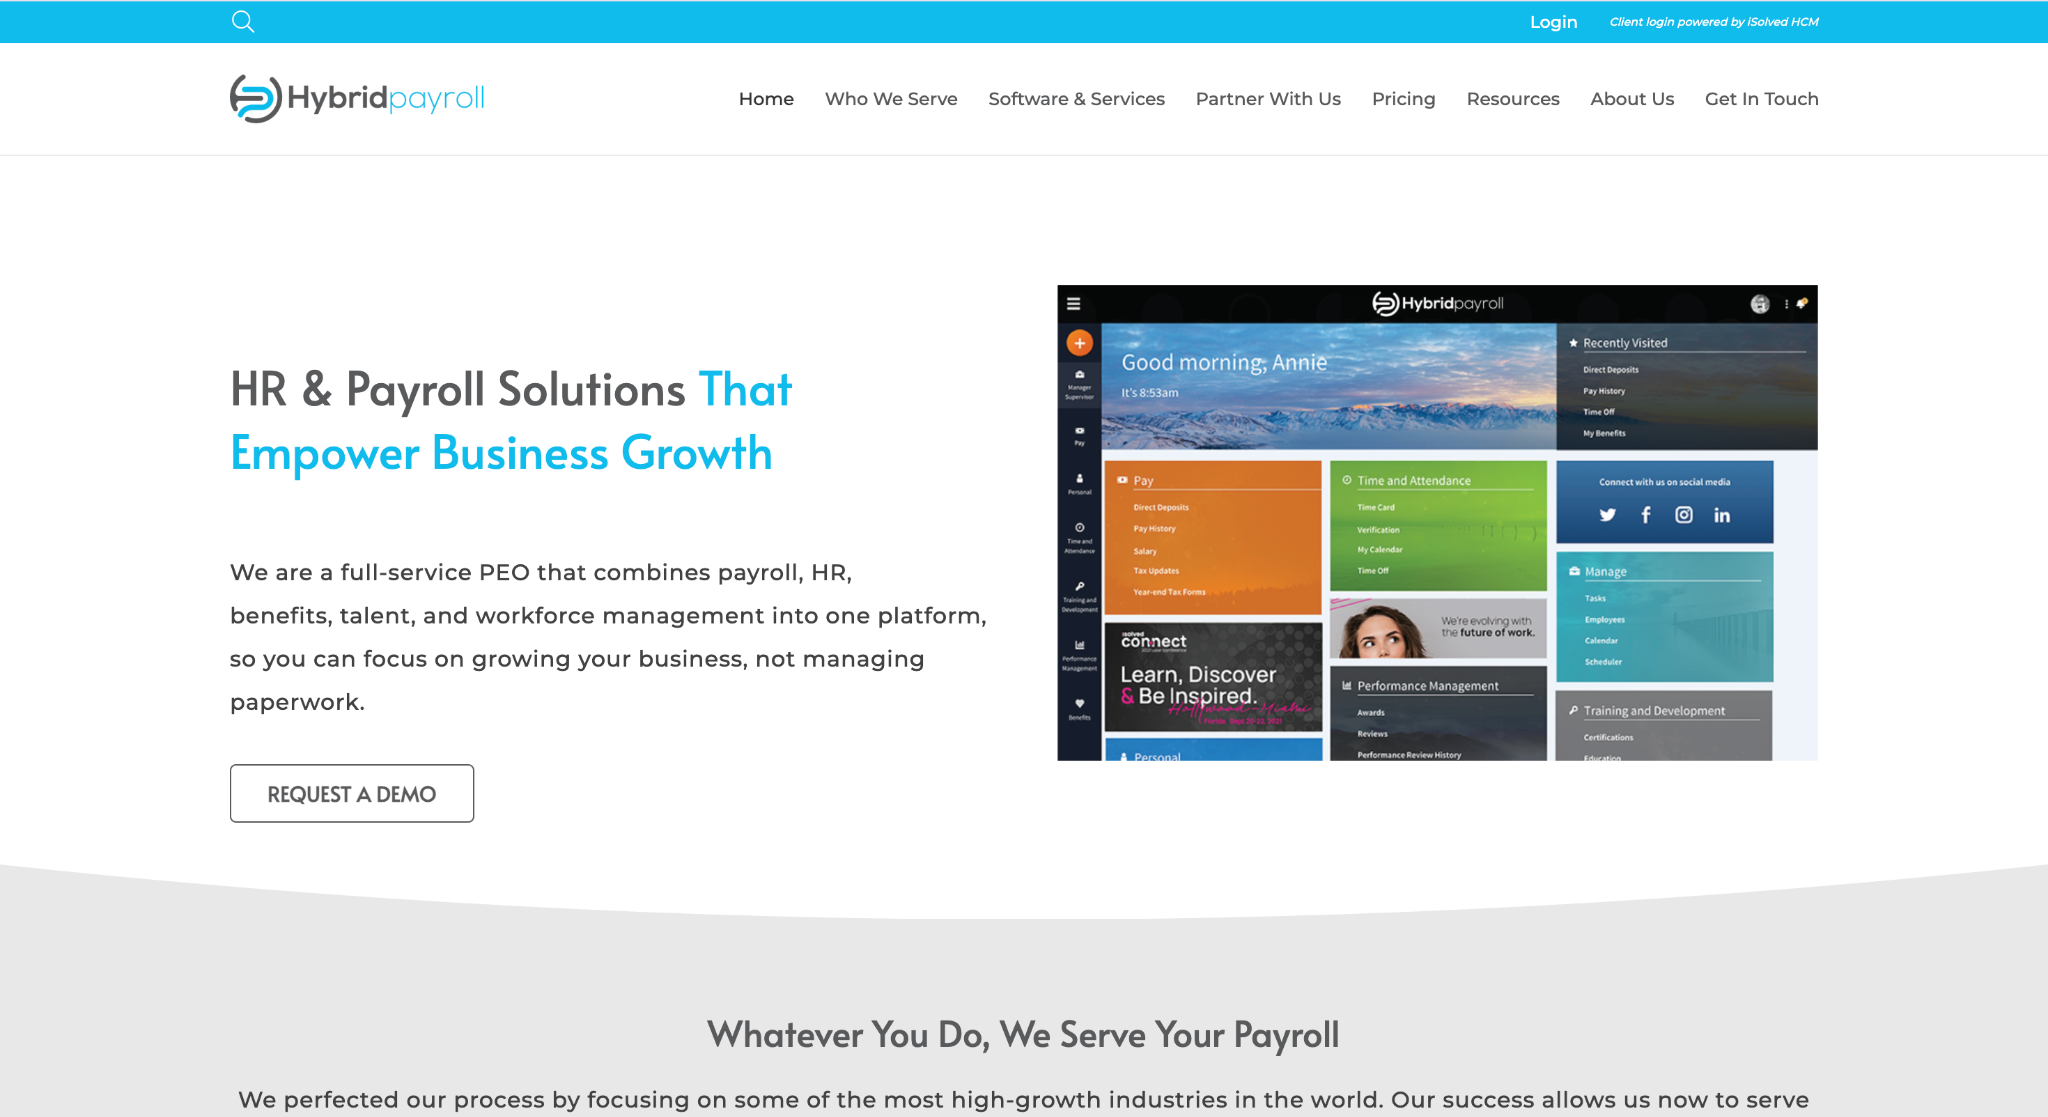
Which Functions Does Hybrid Payroll Perform?

Denver-based since 2014, they operate as both a direct payroll processor and a Professional Employer Organization, which means they handle automated payroll, tax calculations, and compliance management alongside full co-employment services. Being positioned as a leading cannabis payroll company in a major cannabis hub gives them firsthand exposure to the regulatory demands Colorado operators deal with daily. Their bundled HR products are built for specific industries rather than adapted from generic templates, which makes a real difference when cannabis-specific compliance is non-negotiable.

What’s Hybrid Payroll’s Edge in Payroll Software for the Cannabis Industry?

Cannabis businesses dealing with multi-jurisdiction payroll tax codes and 280E-inflated obligations need a provider that understands the industry’s compliance layer from the ground up, not one trying to bend a standard framework to fit. Their PEO structure adds an extra layer of risk protection that standalone payroll processors simply don’t offer, and that’s particularly important when state cannabis labor laws keep shifting.

The Review Roundup:

From what the data shows, businesses using Hybrid Payroll respond positively to the personalized service model and the flexibility that comes with customized HR bundling. That kind of personalized approach is rare at this price tier and reflects well on their positioning within the cannabis payroll software space.

BambooHR – Best for Small to Medium-Sized Business HR and Payroll Management
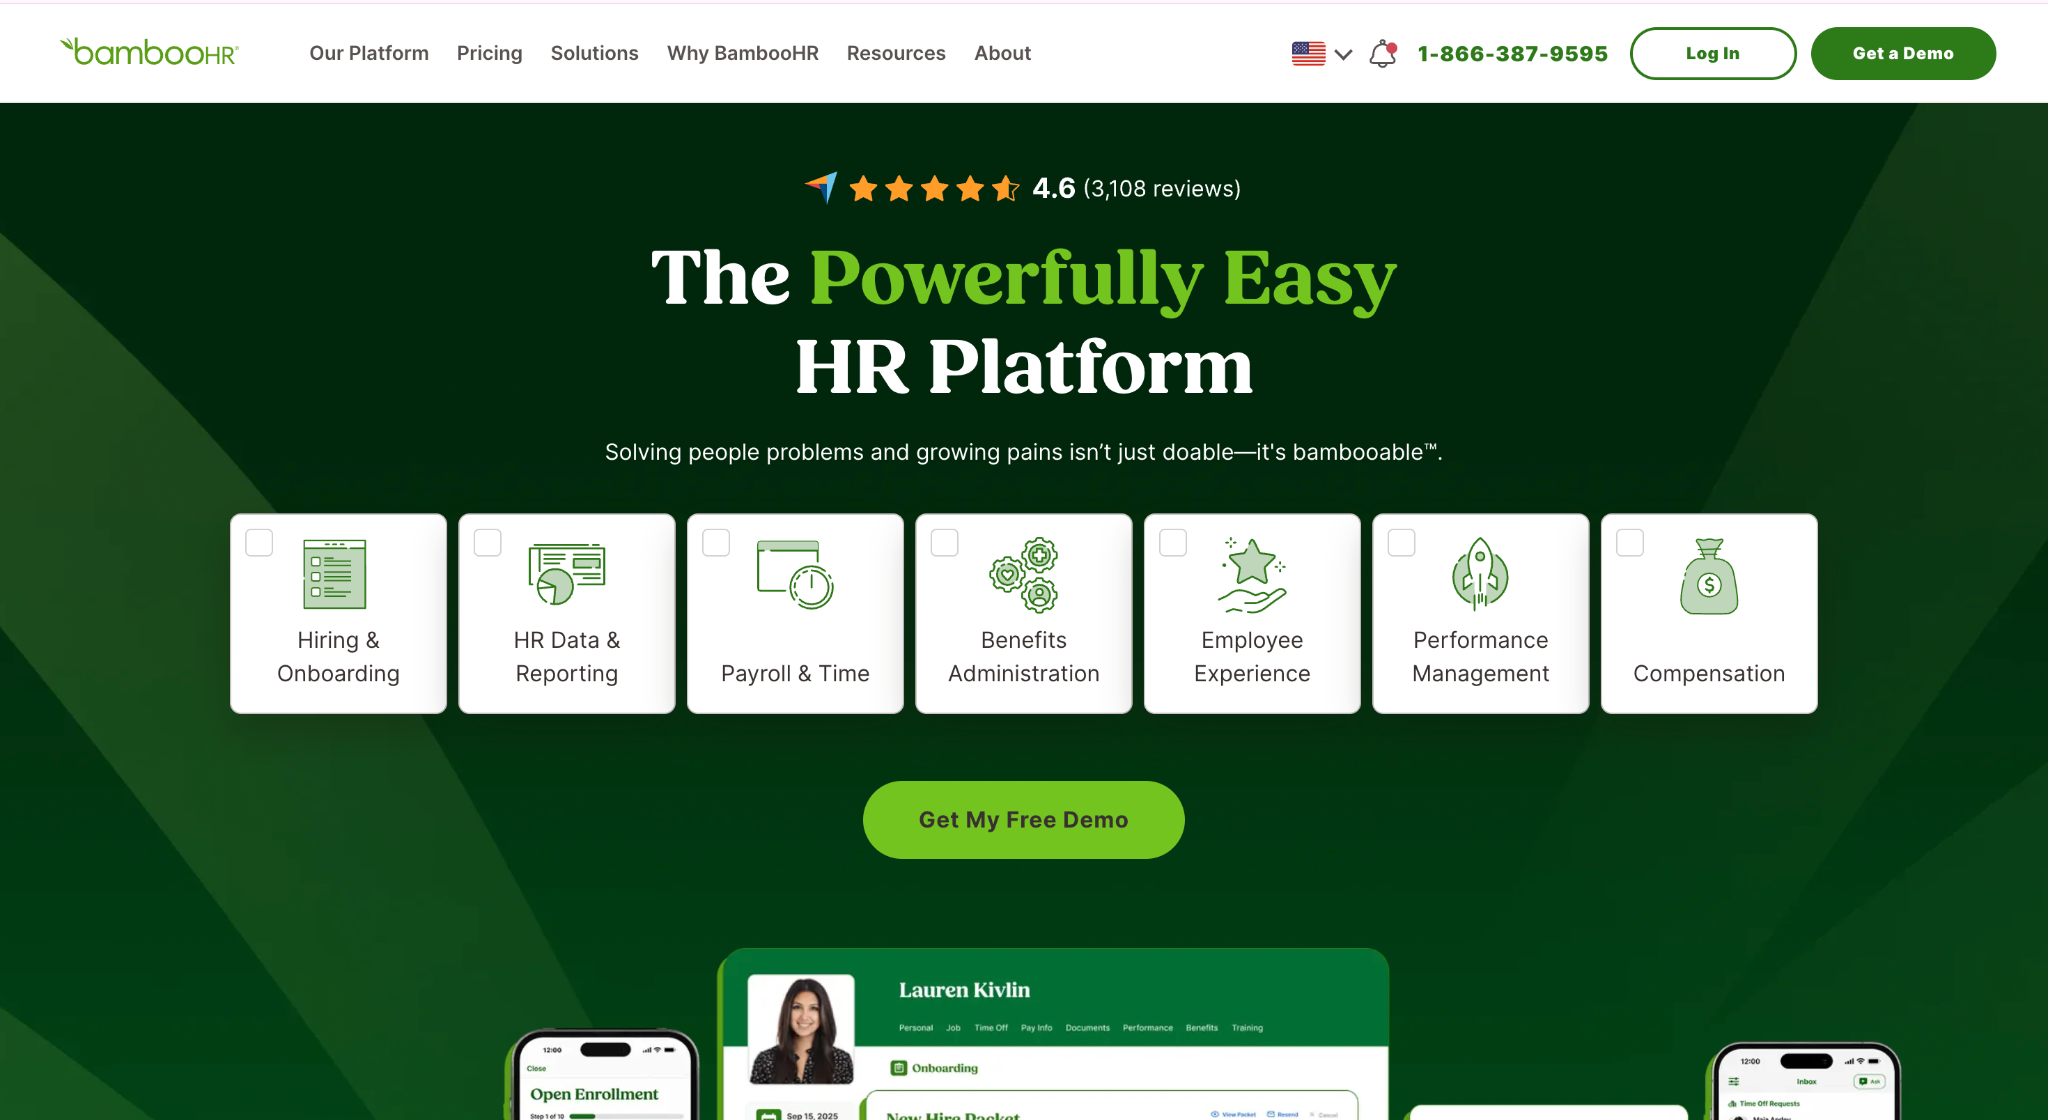
Which Functions Does BambooHR Perform?

BambooHR covers the full HR stack: payroll processing, tax filing, benefits administration, performance management, and talent acquisition, all inside one native platform. They serve over 34,000 customers across 190 countries, which signals serious scalability. The embedded AI and connected ecosystem mean HR workflows don’t require manual intervention at every step, and that reduces the new hire setup and exit process burden that hits cannabis businesses harder than most due to high employee turnover.

What’s BambooHR’s Edge in Payroll Software for the Cannabis Industry?

Cannabis operators managing employees across multiple license types (say, a grow facility alongside a dispensary) need an HR platform that doesn’t fragment data across disconnected tools. BambooHR’s unified architecture addresses exactly that gap. And honestly, the full-service tax filing built into their platform removes one of the more error-prone steps in multi-state cannabis payroll runs.

The Review Roundup:

Users consistently point to the clean interface and the all-in-one structure as the platform’s strongest selling points. The 2025/26 Cloud Awards recognition for Best Cloud HR/HRMS Solution lines up with what practitioners in the field actually say about it being a genuinely cohesive system, not just a collection of bolted-together modules.

Rippling – Best for Enterprise Employee Management and Payroll Automation
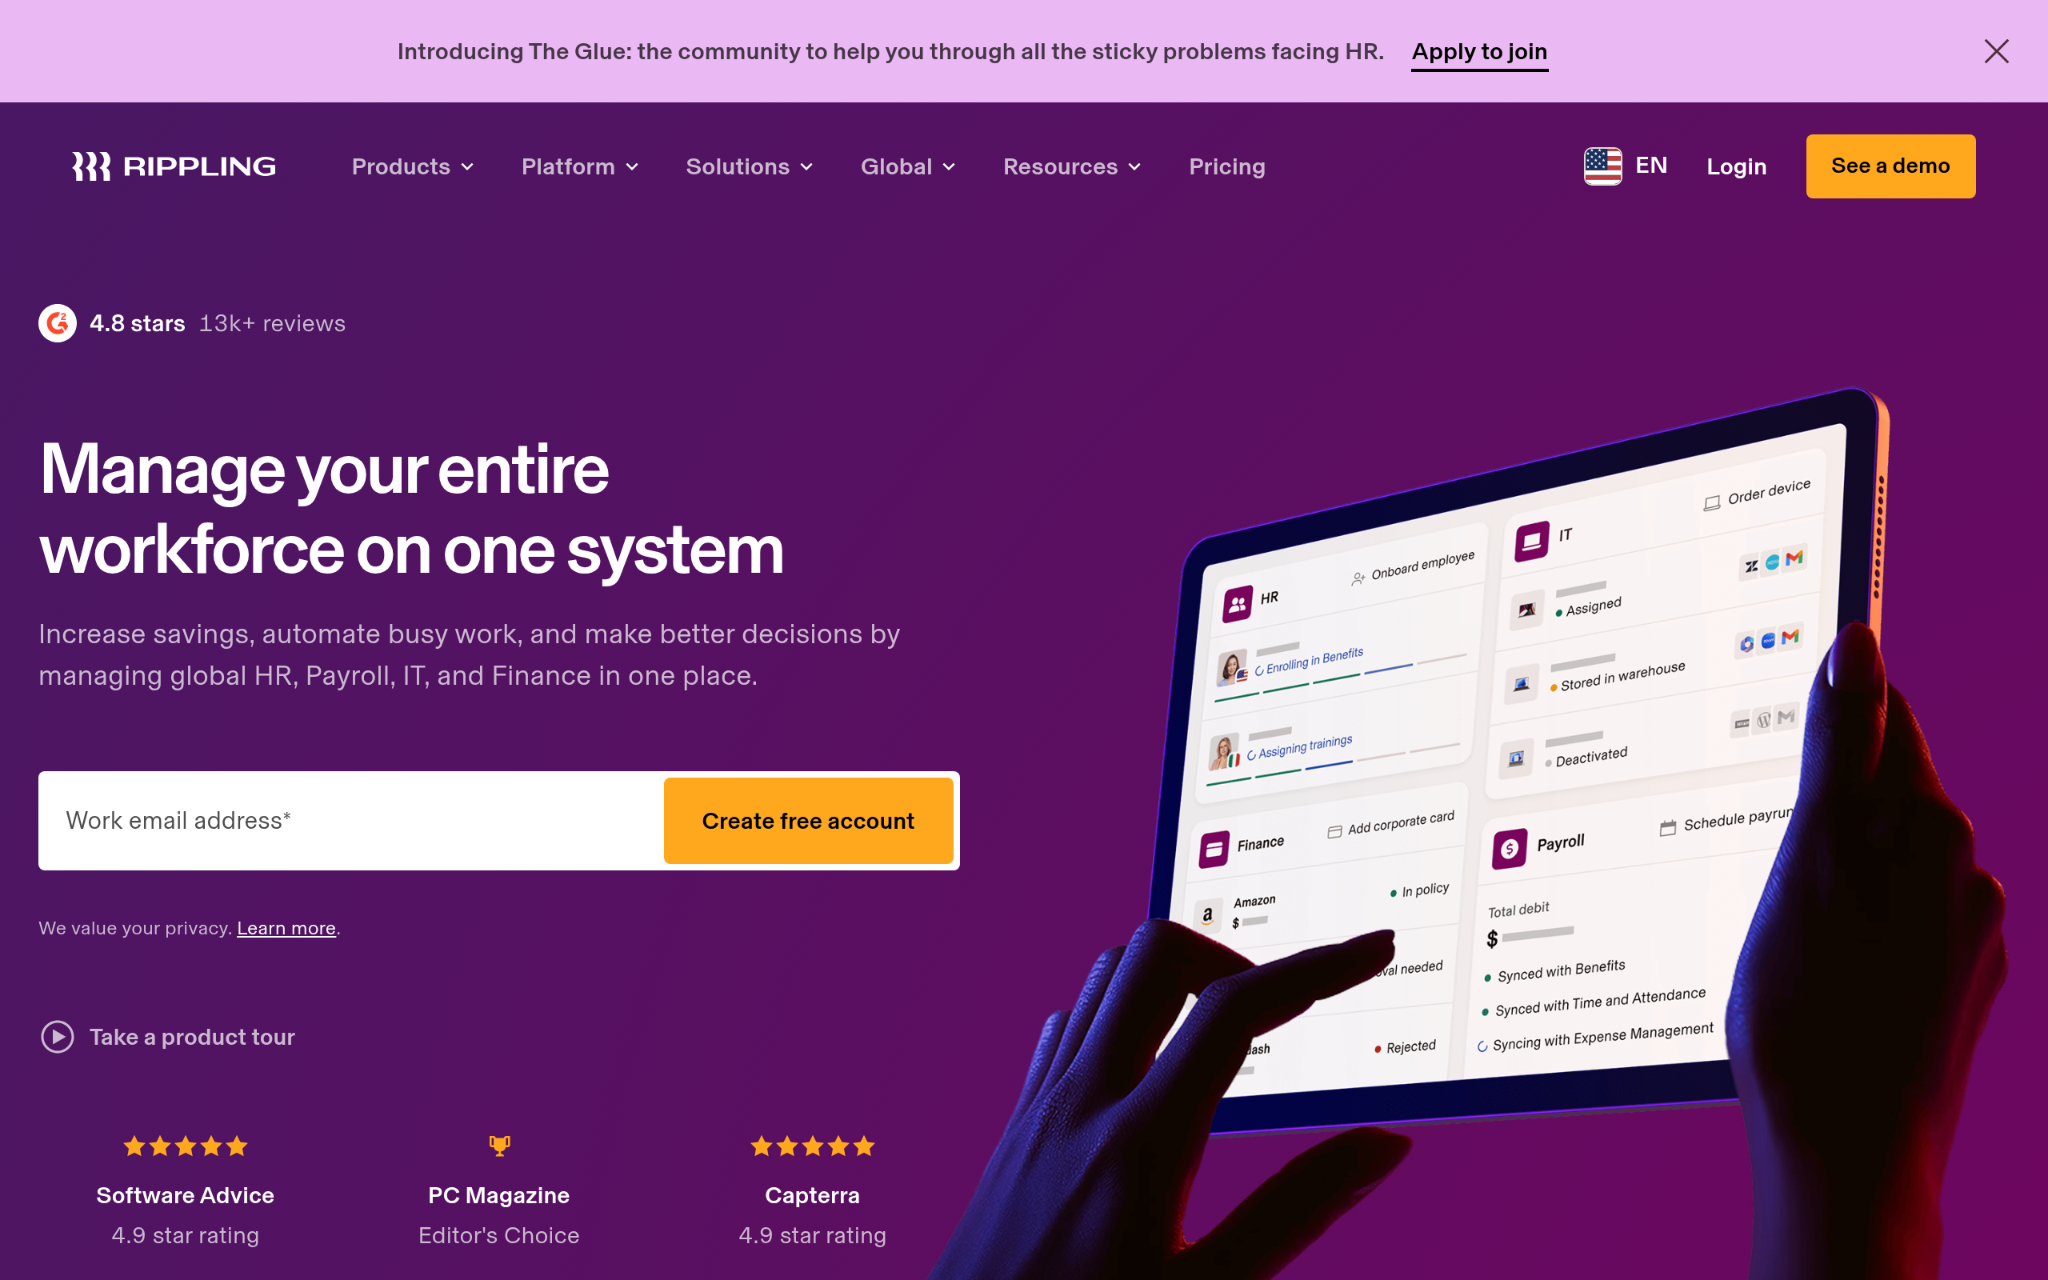
Rippling Screenshot

Which Functions Does Rippling Perform?

Rippling runs on a single source of truth for employee data and connects payroll, devices, apps, benefits, and corporate cards across 500+ connections. The 90-second new hire setup capability is worth noting because cannabis businesses dealing with high turnover spend a disproportionate amount of HR time on that process. Their compliance controls sit at the platform level, meaning rule changes don’t require manual reconfiguration across every system separately.

What’s Rippling’s Edge in Payroll Software for the Cannabis Industry?

For multi-state cannabis operators juggling different license types and locations, Rippling’s ability to manage payroll, compliance, and employee data under one unified system cuts the coordination overhead that typically leads to filing errors. The $16.8 billion valuation following their Series G round signals serious long-term investment in the platform, which matters when you’re building payroll infrastructure that needs to scale.

The Review Roundup:

Rippling earned the number one spot for vendor satisfaction and interface design in payroll and benefits among 10,000+ HR professionals, and that’s not a small sample size. The speed and depth of automation are what practitioners mention most, though the feature density can feel like a lot for smaller operations (think enterprise pricing territory here).

Paychex – Best for Small to Medium-Sized Business Payroll and HR Outsourcing
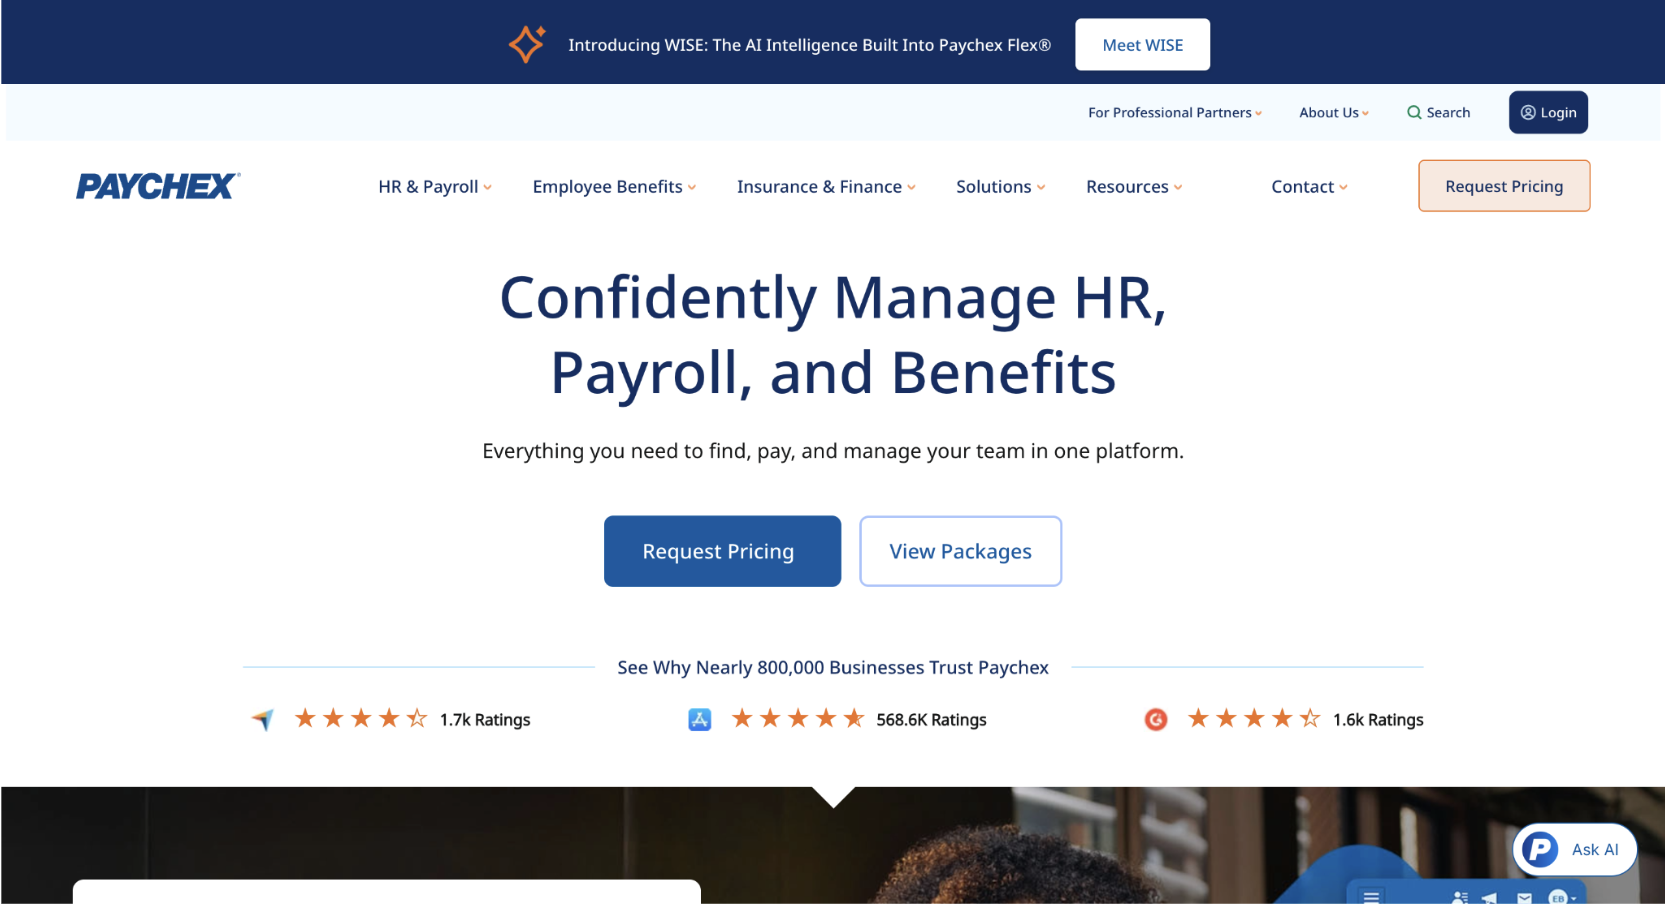
Which Functions Does Paychex Perform?

Founded in 1971, Paychex processes payroll for approximately 800,000 clients across more than 100 offices in the U.S. and Europe. Their SaaS HCM platform covers payroll, HR management, talent acquisition, and workforce management, and they process payroll for roughly 1 in 11 U.S. private sector workers. That kind of scale means their tax filing infrastructure handles real demands across jurisdictions, including the multi-state situations cannabis businesses run into constantly.

What’s Paychex’s Edge in Payroll Software For the Cannabis-Industry?

Cannabis CFOs evaluating payroll outsourcing need a provider with enough infrastructure to handle IRS filings across multiple jurisdictions without errors. Paychex’s 50-plus years of payroll processing experience gives them depth most newer platforms haven’t built yet. Being named to Ethisphere’s World’s Most Ethical Companies list and acknowledged as the largest 401(k) recordkeeper in the U.S. for ten consecutive years reflects well on their reliability, which matters when payroll audit documentation needs to hold up under scrutiny.

The Review Roundup:

Users working with Paychex in regulated industries tend to value the breadth of service options and the established support infrastructure. The Fortune 500 ranking and consistent recognition for staying current suggest a platform that keeps pace with industry changes, though smaller cannabis operations sometimes find the full suite more than they need (not cheap, but worth it for operators who want full outsourcing).

Gusto – Best for Small to Midmarket Business Payroll and HR Management
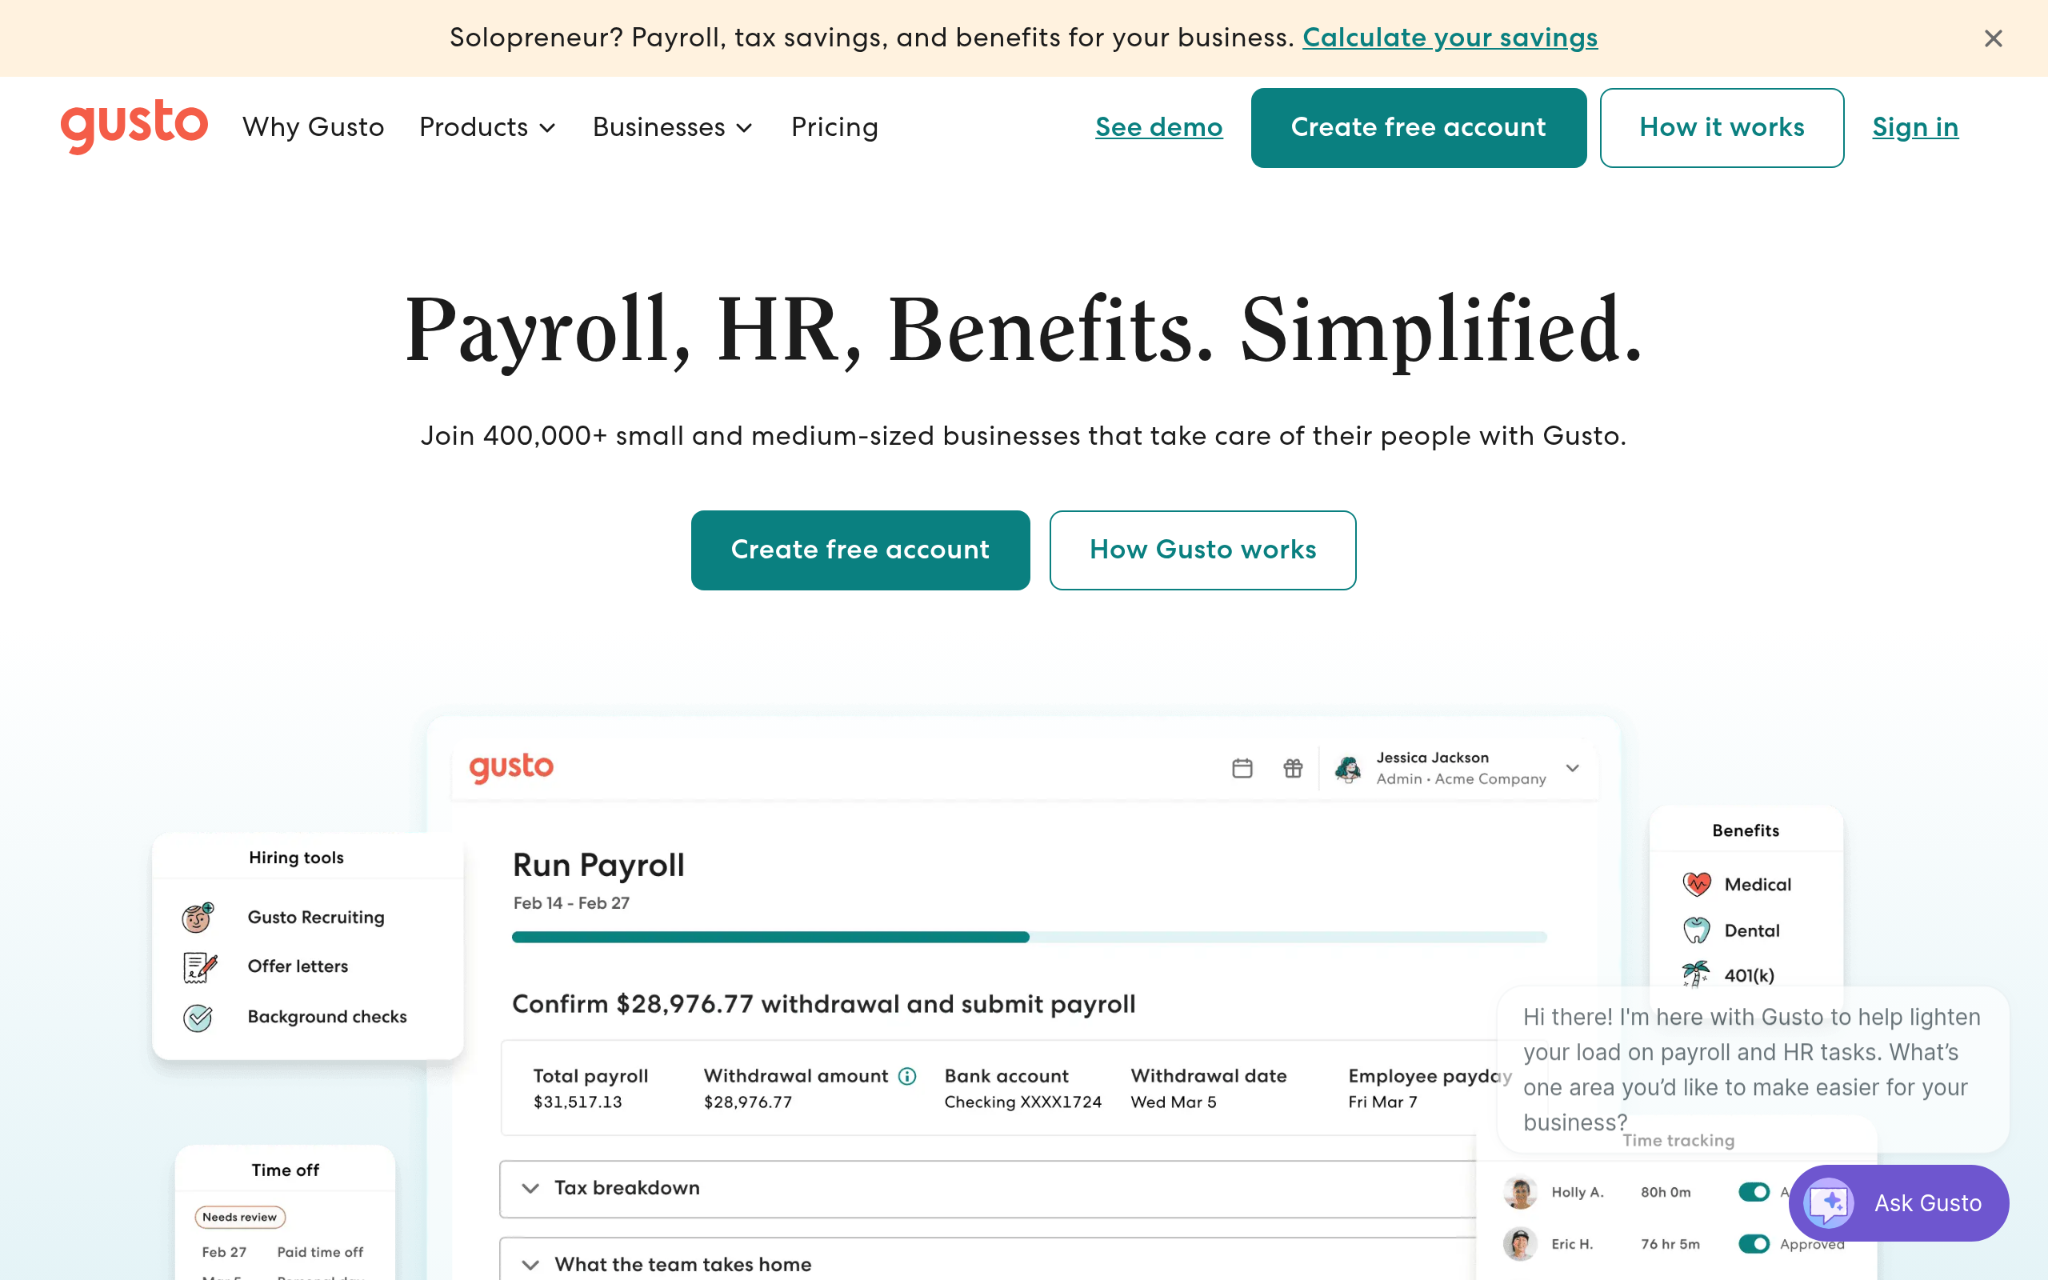
Gusto Screenshot

Which Functions Does Gusto Perform?

Gusto handles payroll processing, automatic tax filing, employee setup, and full benefits administration including health, dental, and vision, all for 400,000 U.S.-based businesses. The automatic payroll tax filing comes at no extra charge, which directly offsets some of the cost pressure cannabis businesses face from 280E’s inflated tax obligations. Their nearly 150 third-party software connections give cannabis operators flexibility to connect with accounting and operations tools they’re already using.

What’s Gusto’s Edge in Payroll Software for the Cannabis Industry?

For smaller cannabis operators who can’t justify a full PEO or enterprise HR platform, Gusto offers a clean, cost-effective path to compliant payroll without requiring a dedicated HR team to run it. Earning the number one Highest Satisfaction Software rating on G2 in 2026 signals that the experience isn’t just functional but genuinely easy to use. That’s a meaningful advantage when your HR team is wearing multiple hats.

The Review Roundup:

Reviewers reliably call out the interface as the platform’s strongest point, and the awards for Best Overall Payroll Processing Software and Best Payroll Software back that up across multiple evaluation cycles. From what the reviews show, the all-in-one approach appeals most to businesses that previously juggled multiple payroll and HR vendors (a common situation for cannabis startups trying to scale fast).

Selection Framework: How Each Pick Was Evaluated

The goal of this evaluation was to identify payroll software options that could genuinely handle the specific demands cannabis businesses face, not just platforms that happen to offer payroll as one feature among many.

Data Collection Methods

The starting point was building a broad list of payroll platforms from software directories, HR technology review sites, industry-specific forums, and product documentation pulled directly from company websites. The initial pool included both general-purpose payroll platforms and providers with documented experience in regulated industries. Each source was cross-referenced to confirm that the platform information was current and reflected the product’s actual state rather than older marketing materials.

Filtering Candidates by Important Criteria

From the initial list, platforms were narrowed down by removing any option without verifiable reviews or documented product capabilities. Review patterns were analyzed across multiple platforms rather than relying on a single rating source. Platforms with inconsistent review histories, outdated feature sets, or gaps in their tax filing documentation were removed from consideration at this stage. The focus stayed on options with enough operational history to assess real-world payroll processing behavior.

Checking Accuracy Against Source Material

Claims made on official product pages were cross-checked against what actual users reported in verified reviews. Where a platform advertised specific capabilities around tax filing accuracy, multi-jurisdiction support, or compliance management, those claims were weighed against the actual review sentiment from HR professionals and business operators. Any major gap between marketing claims and user-reported experience was flagged and factored into the final assessment.

Industry Standing Check

Each platform’s broader reputation was examined through published recognition, industry awards, press mentions, and analyst reports. Platforms that had earned meaningful recognition from credible third-party evaluators, such as software award programs or HR industry publications, carried more weight than those relying solely on self-reported metrics. How long a platform had maintained its standing in the market was also factored in, since payroll software in regulated industries requires sustained reliability over time.

Real-World Payroll Software For Cannabis-Industry Evidence

The final filter focused on whether each platform had visible evidence of handling cannabis-adjacent payroll demands. Dedicated service pages addressing regulated industry payroll, verified case studies referencing multi-state tax compliance, and review documentation from users in complex regulatory environments all contributed to this assessment. Platforms with the strongest real-world evidence across these signals made the final list.

Choosing the Right Payroll Software for the Cannabis Industry: A Quick Guide

Picking payroll software for a cannabis business isn’t the same decision it would be for a restaurant or a retail shop. The IRS 280E burden, multi-jurisdiction tax codes, and state-by-state cannabis operating restrictions create a set of requirements that need deliberate evaluation. Here’s what to look at before committing.

  • Industry/Domain Experience: Look for providers that have worked with cannabis businesses or regulated industries. General payroll experience is useful, but familiarity with Schedule I federal classification realities and state cannabis labor laws saves a lot of painful problem-solving later.
  • Features and Service Options: Confirm the platform handles automated tax calculations, multi-state payroll filing, employee setup and exit processes, and benefits administration. Bonus points for seed-to-sale platform compatibility or cannabis-specific HR documentation.
  • Pricing Structure: Understand whether the pricing model scales with your headcount and license types. Some platforms charge per employee per pay period, others bundle everything into a flat fee. Factor in what 280E compliance cost impact does to your margins before deciding.
  • Results Measurement: Ask how the platform tracks payroll tax filing accuracy rate, time-to-process payroll per pay period, and audit documentation completeness. Platforms that give you visibility into these metrics make compliance reviews far less stressful.
  • Industry Knowledge and Compliance: Confirm the software gets updated when state cannabis regulations change, not six months later. Real-time or near-real-time updates to payroll tax codes are non-negotiable when your operating environment shifts as often as the cannabis industry does.

Wrapping Up

Payroll in cannabis is complicated in ways most other industries never have to deal with. The right payroll software for cannabis-industry businesses reduces your exposure to 280E cost overruns, keeps multi-jurisdiction tax filings accurate, and handles high-turnover new hire setup without falling apart. Whether you’re running a single dispensary or scaling across multiple license types, the options on this list each address different operational profiles. As the cannabis industry matures and more states regulate, demand for purpose-built payroll tools will keep growing.
How Professional Tax Preparation Reduces Risk for Small Business Owners

How Professional Tax Preparation Reduces Risk for Small Business Owners | StrategyDriven Managing Your Finances Article

Running a small business in Indiana involves making decisions that affect profitability, compliance, and long-term growth. While many entrepreneurs confidently manage sales, operations, and customer relationships, tax preparation is an area where even small mistakes can have significant financial consequences. Filing errors, missed deductions, inaccurate payroll reporting, or overlooked tax law changes can result in penalties, interest charges, and unnecessary stress.

Professional tax preparation helps reduce these risks by combining technical expertise with ongoing financial guidance. Rather than simply completing an annual tax return, experienced tax professionals help business owners maintain compliance, improve recordkeeping, and make informed financial decisions throughout the year. For small businesses, this proactive approach often proves far more valuable than attempting to handle increasingly complex tax requirements alone.

Why Professional Tax Preparation Is a Smart Risk Management Strategy

Tax preparation is about much more than meeting a filing deadline. Every business decision, from hiring employees to purchasing equipment, can have tax implications. Professional guidance helps identify potential issues early, reducing the likelihood of costly mistakes while improving overall financial organization.

Here are some of the biggest ways professional tax preparation helps protect small business owners.

1. Audit Red Flags

No tax preparer can promise that a business will never be audited, but professionally prepared tax returns are generally more accurate, consistent, and supported by proper documentation.

Certain filing issues may attract additional scrutiny, including unusually high deductions, inconsistent reporting, mathematical errors, or incomplete financial records. A tax professional reviews returns carefully before submission, ensuring deductions are properly documented and reported according to current tax regulations.

They also help business owners maintain organized records throughout the year, making it easier to respond if tax authorities request additional information. Well-prepared documentation not only simplifies the audit process but also demonstrates that reasonable care was taken when preparing the return.

2. Prevent Costly Filing Errors

Tax laws contain countless rules governing depreciation, business expenses, payroll taxes, estimated tax payments, retirement contributions, and industry-specific deductions. Small errors in any of these areas can result in penalties, delayed refunds, amended returns, or additional tax liabilities.

Professional tax preparers help eliminate many of the mistakes commonly made by business owners preparing returns themselves, including:

  • Incorrect deduction calculations.
  • Missed business expense opportunities.
  • Reporting income inaccurately.
  • Applying the wrong depreciation methods.
  • Filing incorrect business tax forms.

The cost of correcting tax errors often exceeds the cost of professional preparation, making accuracy an important investment rather than simply an expense.

3. Stay Compliant With Changing Tax Laws

Tax legislation changes regularly, and keeping up with those changes can be difficult while running a business. Federal regulations, state tax requirements, filing deadlines, deduction limits, and reporting obligations may all change from year to year.

Professional tax preparers continually monitor these developments and apply current regulations when preparing returns. They can also explain how legislative changes may affect business decisions throughout the year rather than waiting until tax season arrives.

Business owners can also stay informed through the IRS Small Business and Self-Employed Tax Center, which provides guidance on estimated taxes, payroll obligations, recordkeeping requirements, and other compliance topics.

Combining official guidance with professional expertise helps businesses remain compliant while reducing the risk of avoidable penalties.

4. Avoid Payroll and Worker Classification Mistakes

As businesses grow, payroll responsibilities become increasingly complex. Employers must properly classify workers, calculate payroll taxes accurately, and meet reporting deadlines throughout the year.

Misclassifying an employee as an independent contractor, for example, can lead to back taxes, penalties, interest, and additional reporting obligations. Payroll calculation errors may also trigger government inquiries or require corrected filings.

Professional tax advisors help businesses:

  • Classify workers correctly.
  • Meet payroll tax deadlines.
  • Calculate withholdings accurately.
  • Maintain organized payroll records.
  • Comply with federal and state employment tax requirements.

Addressing these issues proactively is significantly easier than correcting them after an audit or regulatory review.

5. Benefit From Year-Round Tax Planning

The greatest value of professional tax preparation often comes outside of tax season. Ongoing tax planning allows businesses to make financial decisions with future tax consequences in mind instead of reacting after the year has already ended.

Regular planning can help businesses improve cash flow, estimate quarterly tax payments more accurately, evaluate equipment purchases, maximize available deductions, and determine whether their current business structure remains the most tax-efficient option.

For many business owners, relying on trusted tax preparation Garrett, IN services helps ensure accurate tax filing while staying ahead of compliance requirements.

Arise Tax works with small businesses throughout Garrett and the surrounding communities, providing tax preparation and advisory services designed to help business owners stay compliant while making informed financial decisions throughout the year.

6. Receive Professional Support During an Audit

Even businesses that maintain excellent records may occasionally receive notices requesting additional documentation or clarification. Without professional assistance, responding to these requests can be stressful and time-consuming.

Experienced tax professionals understand what tax authorities require and can help organize financial records, prepare supporting documentation, and communicate throughout the review process. Their familiarity with tax procedures allows business owners to respond more efficiently while avoiding unnecessary mistakes.

Having professional support also provides peace of mind, particularly for owners who may not be familiar with complex tax regulations or audit procedures.

Choosing the Right Tax Professional

Not every tax preparer offers the same level of expertise for small businesses. Beyond preparing returns accurately, a qualified advisor should understand your industry, business structure, and long-term financial goals.

When evaluating a tax professional, consider whether they:

  • Have experience working with businesses similar to yours.
  • Offer year-round advisory services rather than seasonal filing only.
  • Stay current with federal and state tax law changes.
  • Provide assistance if questions or audits arise.
  • Communicate clearly about tax planning opportunities throughout the year.

A long-term relationship with a knowledgeable tax professional often provides greater value than simply hiring someone to complete an annual return.

Conclusion

Professional tax preparation reduces risk in ways that extend far beyond filing an accurate return. By preventing costly errors, reducing audit risks, maintaining compliance with changing regulations, and providing year-round planning, experienced tax professionals help small business owners make more confident financial decisions.

Rather than spending valuable time navigating complex tax rules, business owners can focus on growing their companies while knowing their tax obligations are being managed accurately and proactively. Over time, that combination of compliance, planning, and professional guidance becomes an important part of building a stronger and more resilient business.

Why Growing Businesses Should Not Wait Until Their Tax Issues Turn Into Legal Issues

Why Growing Businesses Should Not Wait Until Their Tax Issues Turn Into Legal Issues | StrategyDriven Managing Your Finances Article

A developing company faces more and more tax issues as it grows. New markets, new employees, merger & acquisitions, restructuring, or financing may require the attention of tax advisers. This challenge is universal regardless of the country. While a business may operate in Australia, the USA, the UK, Singapore, or Canada, tax governance becomes essential for scaling up even though there are differences in regulations, thresholds, and procedures from one country to another.

Nevertheless, many businesses are mostly focused on the growth of revenue and operations and neglect tax issues until there is a problem. However, a proactive attitude to tax compliance could help to lower risk, increase the effectiveness of the business, and avoid future disputes with the authorities.

To illustrate the importance of this problem, let us discuss the Australian experience of tax compliance, when the Tax Office actively works to ensure that all the organizations meet their obligations and when the tax disputes happen quite fast as soon as a business goes beyond its initial phase of development.

More Complexities as the Business Grows Up

As the company expands, it not only files taxes on time, but also encounters various tax problems connected with foreign expansion, acquisition, financing, incentives, and restructuring. Inability to deal with all these matters might bring extra tax liabilities, fines, and tax controversies.

Australian experience illustrates this process well. For instance, in recent years, there have been numerous tax disputes of large companies concerning their international structures, transfer pricing policies, and significant corporate transactions. What is interesting about these cases is that the main reason for conflict was not the misconduct of the business but merely the complexity of operating across the borders, structures, and transactions without sufficient specialized advice.

The same thing happens in other countries as well. A business that wants to expand its presence in Singapore from the UK or a company from Canada acquiring a subsidiary in the USA is in the same situation – different in details but identical in its essence.

Tax Governance Is Part of Good Strategy

Today, good tax governance is not a job for the finance department anymore. It requires business leaders to think of tax implications of their strategic decisions, including investments, expansions, and organizational changes. This kind of approach will help the business avoid uncertainty and make informed decisions.

The regulators become aware of this idea as well. Thus, Australian tax authorities have started to pay more attention to the corporate tax governance framework by requiring large companies to demonstrate that tax risk is actively managed at the highest management level and not at the operational one.

Those companies that have some documentation about tax governance processes, escalation policy in case of uncertain positions, and board of directors awareness of the tax risk tend to cope with the questions better since they could prove that their decisions were carefully considered.

However, this process is also relevant to mid-size businesses during their first acquisitions, overseas hiring, and organizational changes since tax considerations were neglected from the very beginning of the strategic process.

Do Not Wait Until Your Company Needs an Audit or Tax Dispute

A lot of companies consult a tax lawyer after receiving an audit notice or becoming entangled in the dispute. However, taking into account potential tax risks and problems in advance might help the company to avoid them.

Usually, when an organization receives a notice of audit, it means that it is already too late to take necessary actions. Some positions were made, some transactions were concluded, some documents were collected that might contradict a later position. Therefore, seeking professional advice at the planning stage allows the business to test its assumptions, make corrections, and collect all the documentation.

Companies conducting some significant transactions, facing some tax problems, or carrying out restructures could benefit from consulting experienced tax lawyers. This kind of advice is especially useful in countries like Australia, where the tax controversy has become a separate practice of law with the specialized practitioners familiar with both the technical aspects of tax position and the approaches of the regulators.

Choosing a Proper Tax Adviser

Different law firms specialize in different fields. Therefore, before consulting a tax adviser, the company should examine its practice and experience and make sure that it is suitable for the organization. The majority of commercial firms provide assistance with tax, corporate transactions, dispute resolution, banking and finance, employment, and regulation matters, thus helping a business at any stage of its development.

Moreover, if the organization has some cross-border operations, the company should choose a firm that has enough experience in working in the particular countries and not the firm with a general commercial practice. Firms with tax controversy capabilities, experience in international tax laws, and negotiation with revenue authorities would have much better chances to help a business solve its problems or avoid them in advance than a generalist practice.

Conclusion

Development brings some legal and tax responsibilities to the business. Considering tax issues in advance and consulting the tax lawyers will help the business avoid risks and make better decisions.

The Australian experience demonstrates the importance of this approach: companies that include tax considerations in their strategic plans have a better opportunity to cope with the disputes and, most of the time, to avoid them. No matter what country the company operates in, proactive tax planning is always better than reaction to the problems.

What Every Business Owner Should Understand Before Seeking Debt Relief

What Every Business Owner Should Understand Before Seeking Debt Relief | StrategyDriven Managing Your Finances Article

Deciding to pursue debt relief is a big step — one that comes with real consequences, meaningful benefits, and a fair amount of complexity. Yet many business owners walk into the process without a clear picture of what it actually involves, what it will cost them, or what the realistic outcomes look like.

In a city like Washington, D.C. — where small businesses operate in a high-cost environment shaped by federal policy, shifting government contracts, and one of the most competitive commercial real estate markets in the country — financial pressure on business owners is rarely simple. The debt relief landscape is equally layered.

Before you take any formal steps, here are seven things every business owner should genuinely understand about the debt relief process — the kind of grounded, honest perspective that saves you from costly surprises.

1. Not All Debt Relief Options Are the Same

“Debt relief” is an umbrella term that covers several very different approaches — and they don’t all lead to the same place. Debt consolidation merges multiple obligations into a single loan, usually at a lower interest rate. Debt settlement involves negotiating with creditors to accept less than the full amount owed. A structured repayment plan restructures the timeline without reducing the principal. Bankruptcy, at the far end of the spectrum, provides a legal discharge of qualifying debts.

Each option has different eligibility criteria, credit implications, timelines, and costs. What works for one business may be entirely wrong for another — even in a similar financial position. Understanding this range upfront prevents you from pursuing a path that doesn’t fit your actual situation.

The first conversation with any professional should help you identify which category you actually belong in — not push you toward a predetermined product.

2. Your Credit Will Be Affected — Plan for It

Most forms of business debt relief carry some credit impact. Settlement programs typically require accounts to go past due before negotiations begin — which shows up on credit reports. Consolidation loans affect your utilisation ratio. Bankruptcy, depending on the type, remains on a credit profile for seven to ten years.

This doesn’t mean debt relief is the wrong choice. For many businesses, the short-term credit hit is a reasonable trade for the long-term stability that comes from resolving unmanageable debt. But it does mean you should know what’s coming — so you can plan around it rather than be surprised by it.

Questions worth asking before you start:

  • Will I need business financing in the next 12 to 24 months?
  • Do any key contracts or leases depend on a minimum credit rating?
  • How long will recovery take after the program ends?

3. Timing Changes What’s Possible

The window of available options narrows as a debt situation ages. Early in a financial difficulty — when accounts are still current but cash flow is clearly unsustainable — a business has considerably more negotiating leverage than it does six months later when accounts are in collections and legal action is looming.

Creditors are generally more willing to negotiate modified terms before they’ve classified a debt as a loss. Once an account has been written off and sold to a collections agency, the flexibility shrinks and the conversation becomes more adversarial.

Acting earlier doesn’t mean panic — it means preserving options. A proactive conversation with a specialist when the situation is still developing is almost always more productive than a reactive one after it has deteriorated.

4. Secured and Unsecured Debt Behave Differently

This distinction matters enormously and is frequently misunderstood. Unsecured debts — credit cards, lines of credit, supplier invoices — have no collateral attached and are generally more negotiable. Secured debts — mortgages, vehicle loans, equipment financing — are backed by a physical asset, which changes both the risk and the leverage in any negotiation.

Attempting to include secured debts in a settlement program without understanding the implications can result in asset repossession or foreclosure. Any debt relief strategy needs to be structured around this distinction from the outset — with a clear assessment of which debts can be negotiated and which carry collateral risk.

A qualified professional will categorise your obligations before recommending anything — this is a foundational step, not a formality.

5. Who You Work With Matters As Much As the Plan

The debt relief industry is not uniformly regulated, and not every company offering these services operates with the same standards. Some charge high upfront fees before delivering any results. Others use aggressive sales tactics that push businesses into programs that don’t fit. A few simply take fees and produce nothing of value.

Business owners in the capital region researching their options and looking into debt relief Washington, District of Columbia services should prioritise providers who are transparent about fees, accredited through recognised industry bodies, and willing to explain the full process before any agreement is signed.

Firms such as US National Credit Solutions operate with clear disclosures and works to match businesses with programs suited to their actual financial profile — not the most profitable option for the firm.

6. The Numbers Need to Be Fully Honest

Debt relief works best when it’s built on accurate, complete financial information. That means a full accounting of every obligation — not just the ones keeping you up at night. Business owners sometimes understate what they owe, omit debts they expect to resolve independently, or overestimate incoming revenue. Any of these gaps can result in a plan that looks workable on paper but fails in practice.

Before your first consultation, gather the following:

  • A complete list of all business debts with current balances and interest rates
  • Three to six months of business bank statements
  • A realistic monthly cash flow summary — income and all expenses
  • Details of any personal guarantees tied to business debt

Going in with complete information isn’t just helpful — it’s what makes the difference between a plan that holds and one that unravels after the first unexpected expense.

7. Relief Is a Starting Point, Not a Finish Line

Completing a debt relief program is a genuine achievement — but it doesn’t automatically resolve the conditions that created the debt in the first place. Without addressing the underlying causes — whether that’s an unsustainable pricing model, high overhead, poor receivables management, or seasonal cash flow gaps — the same pressures can resurface.

According to the Federal Deposit Insurance Corporation (FDIC), businesses that pair debt resolution with basic financial management improvements — including cash flow planning and disciplined expense tracking — are significantly more likely to maintain financial stability in the years following a relief program.

The most valuable debt relief programs don’t just negotiate balances — they leave you with a clearer understanding of your finances and a realistic plan for keeping them that way going forward.

Conclusion

Debt relief done well is a powerful tool. It can reduce what you owe, restructure impossible payment terms, stop creditor pressure, and give a struggling business the breathing room it needs to recover. But it works best when you enter the process with clear expectations, honest numbers, and the right professional in your corner.

The seven points above aren’t meant to discourage anyone from seeking help — quite the opposite. They’re meant to make sure that when you do take that step, you take it with your eyes open and your position well prepared.

Understanding the process is the first act of taking back control of it.

What Financing Options Help Small Businesses Grow Faster in Brisbane?

What Financing Options Help Small Businesses Grow Faster in Brisbane? | StrategyDriven Managing Your Finances Article

Brisbane is expanding rapidly. With the population surging and major infrastructure projects ramping up across the city, the opportunities for small businesses are obvious. But growth eats cash. Whether you are taking on a larger warehouse in Richlands, upgrading your software systems, or hiring a new crew to handle government contracts, you need money behind you.

Scaling a business without adequate capital usually leads to burnout or failure. Bank loans used to be the default answer. You would take your business plan to the local branch manager and wait six weeks for a decision. That model is mostly dead. Traditional banks are often too slow and their lending criteria too rigid for fast moving operators. Business owners have to look at the whole board to fund their next phase of growth. Here is a look at the commercial funding mechanisms actually working in the market right now.

Equipment and Asset Finance

If your growth strategy relies on heavy machinery, commercial vehicles, or specialised equipment, paying cash upfront is usually a mistake. Emptying your bank account to buy a physical asset leaves you vulnerable to everyday cash flow gaps.

Asset finance lets you acquire the equipment immediately while spreading the cost over its useful life. The machinery itself acts as the security for the loan. This keeps your working capital intact. For transport and logistics operators working out of Acacia Ridge or the Port, putting the right vehicles on the road quickly is the entire game. If you are looking at truck finance Brisbane, you will find non bank lenders who deal exclusively in the transport sector. They know the commercial lifespan of a prime mover and will structure terms and balloon payments that match your actual revenue cycles. You get the equipment to generate income right away while paying it off in predictable chunks.

Unsecured Business Loans for Speed

Sometimes you do not have a hard asset to secure a loan against. You just need a fast injection of cash to fund a marketing push, buy bulk inventory ahead of peak season, or cover wages while waiting for a major contract to commence.

Unsecured lending has evolved heavily over the last few years. The main trade off is straightforward. You pay a higher interest rate because the lender carries more risk. What you get in return is speed. Many alternative lenders can approve and fund a loan in 24 hours just by connecting to your Xero or MYOB account and reviewing your recent bank statements. For a retail or hospitality venue wanting to renovate quickly, the fast access to funds easily outweighs the higher cost of capital. The key is knowing exactly how the funds will generate a return to cover the debt.

Invoice Financing for B2B Operations

Waiting 30 to 60 days for clients to pay their invoices is a massive handbrake on growth. It forces you to act as a free credit facility for your larger clients.

Invoice finance changes this dynamic. It allows you to access up to 80 percent of the value of your outstanding invoices almost immediately. The lender advances you the cash upfront. When your client finally pays the invoice, the lender passes on the remaining 20 percent minus their facility fee.

This effectively turns your accounts receivable into liquid cash. You are not taking on debt in the traditional sense. You are just paying a premium to access your own money faster. For manufacturing, wholesale, and labour hire businesses in Brisbane, this structure is highly effective for smoothing out lumpy cash flow.

Overdrafts and Lines of Credit

A business line of credit works basically like a large credit card. You are approved for a set limit and you only pay interest on the funds you actually draw down.

This is one of the most practical tools for managing seasonal fluctuations. If you run a service business, having a revolving line of credit sits in the background as a safety net. You draw on it to pay suppliers when cash is tight and pay it back down to zero when your major invoices clear.

Getting a facility set up requires strong historical finances. Banks and alternative lenders will look closely at your trading history and ATO compliance. Once it is established, it requires very little daily management.

Alternative Asset Liquidity

When credit markets tighten, traditional lenders pull back their risk appetite. Business owners often have to look at their own balance sheets and personal holdings to fund their next strategic move. This is where alternative and physical assets come into play.

Some founders choose to liquidate or borrow against physical investments to inject cash into their business quickly without jumping through endless banking hoops. I have seen founders quietly turn to Brisbane bullion dealers to offload company owned or personal precious metal reserves when they need immediate capital. Gold and silver are highly liquid. Converting them to cash can bridge a sudden funding gap much faster than waiting for a commercial property refinance to clear. It is a niche approach but highly effective for those who hold physical reserves.

Private Equity and Angel Investment

Taking on debt is not the only way to fund growth. Bringing in outside investors exchanges a percentage of your company equity for cash.

Brisbane has an active angel investor network. Selling equity means you do not have to worry about monthly loan repayments draining your cash flow while you try to build the business. The money can be put entirely toward product development, marketing, and scaling the team.

The downside is the long term cost. Giving up 15 percent of your company might solve your cash problem today, but that 15 percent could be worth millions in five years. You also give up a degree of control. Investors will want a say in how the business is run and will expect regular reporting on your metrics.

Structuring Your Debt Correctly

There is no single correct way to fund a company. The best operators use a strategic mix of these tools. They might use asset finance for their fleet, an unsecured loan for a one off inventory purchase, and a line of credit for seasonal wage management.

The goal is always to match the type of finance to the purpose of the funds. 

  • Do not use a short term unsecured loan to buy an asset you will use for a decade. 
  • Do not tie up your family home as security just to cover a temporary cash flow dip. 

Get the funding structure right from the start. If you mix short term debt with long term assets, you put the business under immediate repayment pressure. Good financial hygiene means sitting down with your accountant or commercial broker and mapping out exactly what the capital is for, how long it will take to generate a return, and what happens if the market turns. 

Debt is just a tool. It only becomes a burden when you use the wrong product for the job.