Most property investors I meet have left four figures on the table, and they don’t find out until someone else does their paperwork. The mistake almost never comes from dishonesty. It comes from a quiet assumption that the accountant will “sort it out” at tax time, when the person who could actually find the money was never in the room.
Here’s what I promise you in this piece: the four places claims fall apart, the one document that decides whether you get a refund or a letter from the tax office, and a straight answer on whether a schedule is worth ordering for a property you bought twelve years ago. If you own a rental, especially one you’ve been holding for a while, read all the way to the checklist at the bottom.
Plenty of owners start by pricing a report themselves and searching something like Tax Depreciation Sunshine coast to see what a local provider charges, which is sensible. What isn’t sensible is paying for the report before you understand what you’re actually asking for.
What the Deduction Actually Is
Depreciation on a rental property is the tax office’s way of letting you write off the slow wear and tear of a building and everything inside it. Two separate things get claimed, and they behave nothing alike.
Capital works: the structure itself, bricks, roof, plumbing, fixed fixtures. Claimed over a long horizon, typically decades.
Plant and equipment: the stuff you can physically pick up and carry out of the house. Ovens, carpets, blinds, air conditioners, hot water systems.
Owners blur these together constantly. The building doesn’t devalue the same way a washing machine does, and if you list a dishwasher under the structural line, you lose years of claimable value on an item that could have been written down far faster. The rules changed for secondhand plant and equipment in recent years, which is exactly why you don’t guess. Baseline guidance from the Australian Taxation Office sets out what rental owners can and can’t claim, and it’s worth reading once before you sign anything.
Where Claims Actually Go Wrong
Four failures show up again and again. Three of them cost you money, and the fourth costs you sleep.
Guessing the construction date. The date a building went up decides whether you can claim capital works at all. Owners guess based on the vibe of the kitchen. Then the quantity surveyor pulls the council records and the guess was wrong by a decade.
Skipping older properties. I hear the same line weekly: “It was built in the seventies, there’s nothing to claim.” A thirty year old building without renovations still carries structural value, and the renovation history often hides a second layer of claimable works. I’ve seen owners walk away from five figure deductions because the house looked old. Looks mean nothing here.
Treating a renovation as a single line item. You spent a lump sum on a new kitchen. That lump isn’t one number on a tax return. It splits into cabinets, benchtops, appliances, plumbing work. Each piece has its own lifespan and its own deduction rate. This is the single most common place cash quietly disappears, and my honest opinion is that any renovation over a few thousand dollars deserves its own schedule.
Buying the schedule too late. You can claim prior years, but you need the report in hand to amend past returns. Ordering in June, days before the deadline, means the provider is rushed and your accountant is scrambling.
Why a Quantity Surveyor, and Not Your Accountant
Your accountant knows tax law. They do not know how to estimate the replacement cost of 1980s brickwork and a tiled roof. That estimate requires construction cost data, and in Australia the tax office expects the person preparing that estimate to hold the right qualifications.
So you get two documents from a good provider: an estimate of construction cost, then a depreciation schedule built from it. When I look at a report, I check three things. Does the property description match exactly, including the garage and the shed? Are all the appliances listed with realistic values? Does it read like someone walked the property or studied plans, rather than filled a template? A schedule that takes twenty minutes to prepare and a schedule that takes two days look different on the page, and the tax office can tell which one you have.
The Rental Connection Most Owners Miss
Losing a tenant costs more than lost rent. It costs you the chance to re-let at the right price in the right month. Nationally, the Australian Bureau of Statistics tracks rental market conditions, and any suburb with tight vacancy is one where a tenant leaving throws your whole cash flow plan off. Deductions you’ve banked from depreciation create a buffer for exactly those months, which is why I’d rather see a landlord over-claim their paperwork and under-worry their cash flow.
There’s a wider point here too. Depreciation sits inside the operating economics of ownership, and small business operators in every sector watch those numbers because they decide how long an asset keeps earning. The Bureau of Labor Statistics tracks the cost of doing business across sectors for the same reason. Your rental is a small business with a roof, and it deserves the same scrutiny you’d give a delivery van.
Your Pre-order Checklist
Run this before you pay anyone a dollar.
1. Find the construction date from council records, not from the agent’s memory. 2. Gather every invoice from renovations in the last decade. If you renovated, list each item separately even if the builder billed one total. 3. List every appliance and fixture, including the cheap ones. Blinds and carpets count. 4. Confirm the provider is a qualified quantity surveyor registered as a tax agent. 5. Ask what happens if the report misses something. A provider who stands behind their work will answer plainly. 6. Diary the date you’ll hand the report to your accountant. Leave a week of buffer.
Is It Worth It for an Older Property?
Yes, and I’ll say that flatly. The maths works the other way around. A newer build has obvious, easy deductions. An older property is where a good surveyor finds what an optimistic amateur misses. The fee is also claimable, so the net cost of getting it right sits well below what a missed deduction costs you over one tax year, let alone five.
The one case where I’d hold off: a property you’re selling within the next few months, where the amended return has little runway. Even then, the deduction follows the property value, so mention it to your buyer’s side. It’s a quiet selling point.
Getting This Right the First Time
You now know the two categories that must never be merged, the four ways claims fail, and why the estimate and the schedule are two different documents from the same qualified hand. You have a checklist you can run this weekend and a clear reason to order the report early rather than in a panic.
So here’s the question I’d leave with you: when did you last look at your rental property the way you’d look at any asset that earns you money? If the answer is never, order the schedule before your next return and see what the building has been quietly owing you.
https://www.strategydriven.com/wp-content/uploads/125124.jpg10871500StrategyDriven - Sponsored Contenthttps://www.strategydriven.com/wp-content/uploads/SDELogo5-300x70-300x70.pngStrategyDriven - Sponsored Content2026-10-28 22:22:452026-10-28 22:22:45What Landlords Get Wrong About Property Tax Deductions
For a salon with uneven books, funding that moves with sales can be a useful starting point. Revenue-based working capital can cover slow months, while equipment financing spreads long-life assets over time and a revolving line handles inventory gaps. That combination matters when appointment books swing with weddings, holidays, prom season, and summer slowdowns. U.S. salon, spa, barbershop, and med-spa owners can use this guide to compare financing providers in 2026, recognizing the beauty salon’s mix of services and retail sales.
Our top pick is Platform Funding for salon owners managing seasonal swings, because its revenue-based funding collects repayments as a percentage of daily sales. It advertises a funding decision within 24 to 48 hours, subject to application review, on amounts between $5,000 and $3 million with no collateral required, and underwriting weighs monthly revenue more heavily than credit score alone. For owners focused specifically on equipment financing with longer repayment terms, Monera Capital is our preferred alternative. For operators who prioritize rapid initial approvals, Rise Business Funding is another option worth considering.
We compared each provider on speed, repayment structure, funding range, eligibility, product breadth, and beauty industry specialization. You will find working capital alongside equipment financing and lines of credit below, with best-for guidance covering single locations and multi-location groups as well as equipment-heavy med-spas. Eligibility and terms vary by state. The eight options that follow are ranked for their fit with seasonal cash flow rather than headline funding size alone.
Provider
Top Use Case
Platform Funding
Seasonal revenue-based repayment
Shim Capital
High-ticket funding and SBA access
Rise Business Funding
Rapid initial approval
Direct Fast Funding
Multi-location and same-day capital
Monera Capital
Equipment financing with longer terms
SBG Funding
Revolving credit and soft pre-qualification
Pincutt
Aesthetic and med-spa equipment financing
Clara Capital
A dedicated relationship-based lending partner
How We Chose
We compared providers with seasonal cash flow in mind, rather than relying on generic small business criteria. Each needed a plausible fit for appointment-based revenue and a clear path from application to funds.
Speed From Application to Funds
We distinguished advertised approval times from funding decisions and actual disbursement, and favored providers that state timelines clearly.
Repayment Structure and Seasonal Fit
We favored percentage-of-sales or appointment-aware structures for working capital, alongside fixed schedules where they suit equipment, because salon financing has to work in both peak and slow weeks.
Funding Range and Use Cases
We considered minimums and maximums against real salon needs, from a single station refresh to a full build-out or second location.
Eligibility and Underwriting
We looked at monthly revenue thresholds and time in business, along with how much weight is placed on credit score versus cash flow.
Product Breadth Beyond Term Loans
We credited working capital plus equipment financing and revolving lines, since seasonal operators often need more than one tool.
Beauty Industry Specialization
We preferred providers that describe salon, spa, barbershop, and aesthetic workflows specifically rather than treating beauty as an afterthought.
The 8 Best Salon Financing Providers for Managing Seasonal Cash Flow
The providers below cover different needs for beauty operators, whether that is a single-chair studio bridging a slow February or a multi-location group financing new treatment rooms. Each earns its place for a different seasonal problem. Number one is our top overall recommendation for owners whose revenue rises and falls by week.
1. Platform Funding – Best Overall for Seasonal Revenue-based Repayment
Platform Funding is our preferred fit for salons that need repayments to adjust with the appointment book. For its revenue-based funding option, Platform Funding collects repayment as a percentage of daily sales, so payments step down automatically in slow weeks and step up when chairs are full. That structure addresses the seasonal mismatch between fluctuating sales and fixed monthly loan payments.
The provider advertises a 24 to 48 hour turnaround on funding decisions, depending on the application, with amounts running from $5,000 up to $3 million. That range covers a single styling station or back-bar restock at the low end and a full renovation or multi-location build-out at the high end. No collateral is required, and underwriting prioritizes monthly revenue over credit score alone. To qualify, a salon needs six months of operating history and $12,500 in monthly revenue. In beauty business financing, that profile suits established single locations, growing barbershops, spas, and aesthetic studios that can show steady sales even if bookings vary considerably across the calendar. The company says it has funded more than 30,000 businesses with over $2 billion in total. Use cases include stations and laser or aesthetic devices, as well as renovations, hiring, and new locations.
Key specs:
Amounts: $5,000 to $3 million
Advertised decision turnaround: 24 to 48 hours, depending on the application
Revenue-based repayment option tied to daily sales
No collateral required
Underwriting focused on monthly revenue
Eligibility: $12,500 in monthly revenue and 6 months in business
Serves salons, spas, barbershops, and aesthetic studios
Pros
Percentage-of-sales collection on the revenue-based option lowers payment pressure in slow periods without a separate hardship request
The advertised decision window may suit owners facing payroll, inventory, or lease timing pressure
Wide range handles both small equipment additions and large expansion projects
No collateral requirement helps renters and owners without heavy fixed assets
Revenue-weighted underwriting helps owners with solid books but imperfect credit
Cons
$12,500 per month minimum means very early-stage or part-time studios may not yet qualify
Variable payment timing means the payoff schedule shifts with sales, which feels less predictable than a fixed monthly plan for owners who prefer certainty
Six-month minimum time in business excludes true startups
Ideal for: owners of established salons, spas, barbershops, and aesthetic studios who want flexible capital that adjusts to seasonal revenue, with a relatively short advertised decision window.
2. Shim Capital – Best for High-ticket Funding and SBA Access
Shim Capital is positioned for beauty businesses planning larger moves that exceed typical working capital amounts. The provider describes funding from $25,000 to $5,000,000 for salons, spas, med-spas, and beauty businesses, with capital structured around how the business earns. Products span working capital alongside SBA loans and lines of credit through a single application.
That breadth is the appeal for owners weighing a second location, a full renovation, or a high-cost device suite against slower, lower-cost SBA timelines. Stated uses include build-outs and renovations, equipment, retail and back-bar product, hiring and training, memberships and marketing, and opening another location. For seasonal operators, access to a line of credit matters because it can bridge inventory and staffing before peak wedding and holiday periods, while longer-term SBA pathways can fund structural expansion.
Pros
$5 million upper limit supports multi-location build-outs and comprehensive equipment refreshes
Access to SBA and line-of-credit pathways alongside working capital gives planning flexibility
Beauty-specific positioning covers salons, spas, and med-spas rather than generic retail
Cons
$25,000 floor is higher than needed for single-item purchases or very small studios
Best for:established salons and med-spas seeking larger amounts or SBA and line-of-credit pathways in addition to working capital.
3. Rise Business Funding – Best for Rapid Initial Approval
Rise Business Funding emphasizes rapid initial approvals for beauty and wellness operators that cannot wait for a traditional review cycle. The company advertises approval in as little as 2 hours in some cases, a short advertised turnaround for owners comparing the options in this list. Coverage extends across hair salons, day spas, nail studios, barbershops, med-spas, fitness studios, and wellness centers.
Funding is described for equipment and furniture, renovations, product inventory, and marketing that fills books, with repayment aligned to appointment revenue. That approach is relevant for businesses where Tuesday looks nothing like Saturday. For seasonal gaps, the practical use is covering payroll and product purchases, along with marketing spend ahead of a known peak, without pausing operations. Owners should treat the 2-hour figure as an advertised approval benchmark for qualified files, not a promise of same-hour disbursement in every case.
Pros
Advertised 2-hour approval in some cases suits urgent staffing, inventory, or repair needs
Repayment aligned with appointment revenue fits irregular weekly booking patterns
Single provider can cover combined salon, spa, and wellness formats
Cons
A rapid initial approval does not settle the repayment decision; owners should compare the proposed schedule and overall cost before accepting
Best for: salon and wellness owners who prioritize a rapid initial approval decision while still comparing the full funding terms.
4. Direct Fast Funding – Best for Multi-location and Same-day Capital
Direct Fast Funding focuses on beauty and wellness operators that need capital deployed quickly, from independents to multi-location chains. The provider says it can fund in 4 hours in some cases, with capital for equipment and stations, build-out, expansion, marketing, and second locations. That advertised same-day timing is aimed at moments like a sudden equipment failure, a lease opening, or a hiring window that cannot wait.
The equipment scope is specific and useful: salon stations, chairs, dryers, shampoo bowls, spa beds, treatment equipment, plus laser and aesthetic devices. Build-out and refresh work is also included, with treatment room additions among the uses. Timing matters here. For seasonal management, the value is having capital before demand arrives, whether that means refreshing dated space before prom and wedding season or adding capacity before the holidays. As with any expedited product, owners with non-urgent needs should compare cost and term structures against slower options.
Pros
Advertised 4-hour funding in some cases helps with time-sensitive operational needs
Explicitly serves both single-location independents and multi-location chains
Detailed equipment coverage includes core salon equipment plus spa and aesthetic devices
Cons
Same-day availability is conditional, so owners facing a firm payment deadline should ask when their particular application could reach disbursement
Best for: independent operators and multi-location beauty groups that need capital deployed the same day in some cases.
5. Monera Capital – Best for Equipment Financing With Longer Terms
Monera Capital is the equipment-focused choice in this list, with financing for styling stations, chairs, dryers, and salon and spa equipment on terms up to 60 months. For owners comparing salon financing for equipment purchases, the longer term is the appeal because it spreads a durable asset over more seasons. The equipment itself acts as collateral for that financing.
The provider describes peaks tied to weddings, holidays, and prom season alongside the need for skilled staff and well-equipped stations. That seasonal awareness matters when an owner is deciding between paying cash for chairs and tables versus preserving cash for payroll and product. At the same amount and rate, a longer term lowers the monthly obligation but can increase total interest paid. Equipment finance is asset-specific, so owners who also need unrestricted working capital or a revolving line should consider those needs separately when choosing their funding mix.
Pros
Terms up to 60 months spread equipment costs over several seasonal cycles
The financed equipment secures the transaction; review any additional security or guarantee requirements
Seasonal demand patterns are reflected in the industry approach
Cons
Asset-specific equipment financing is not a substitute for unrestricted working capital or revolving credit
The financed equipment serves as collateral, which differs from no-collateral working capital models
Best for: salons and spas financing defined equipment purchases that benefit from extended repayment terms.
6. SBG Funding – Best for Revolving Credit and Soft Pre-qualification
SBG Funding earns its place for flexibility, pairing equipment financing with a revolving business line of credit. The line is designed to be drawn for product inventory and operating costs during slow seasons, repaid as revenue returns, then drawn again. That repeat access suits salons that stock up before peaks and tighten spending during quieter periods.
Equipment financing covers chairs, wash stations, treatment tables, and specialty equipment without a large upfront cash outlay. Stated project uses include new stations and renovations, as well as additional treatment rooms and new-location build-outs. Pre-qualification is described as not impacting the credit score, which lets owners explore options without a hard inquiry at the first step. The trade-off with any revolving facility is discipline. Owners who prefer a defined payoff date and a fixed schedule may find a term product more comfortable than an open line.
Pros
Revolving line supports seasonal draw and repay cycles for inventory and operating costs
Soft pre-qualification lets owners assess fit without affecting their credit profile at that stage
Equipment and working capital pathways available from one provider
Cons
Open-ended revolving credit requires active management compared with a fixed payoff schedule
Best for: salon owners who want revolving access for seasonal costs plus a soft pre-qualification first step.
7. Pincutt – Best for Aesthetic and Med-spa Equipment Financing
Pincutt focuses on the higher-ticket treatment side of beauty, including med-spas, aesthetic studios, lash and brow studios, nail studios, hair salons, barbershops, and wellness brands. The specialty is financing for laser, IPL, and microneedling systems, where the machine itself can drive premium service revenue. The provider illustrates the math as owning the device and charging per treatment to pay it down over time.
Owners are matched with lenders described as understanding salons and spas, with funding in 24-72 hours in some cases. That match model is distinct from direct lending. It can help niche operators find a lender comfortable with aesthetic device economics, but final pricing and terms come from the matched lender and need a line-by-line review before acceptance. For seasonal planning, adding a sought-after treatment before peak event season can lift average ticket without adding chairs.
Pros
Specialist focus on laser, IPL, and microneedling systems with lender matching suited to treatment economics
Advertised 24-72 hour funding window in some cases supports timely device installs and launches
Covers the full beauty vertical from barbershops to med-spas
Cons
Operates as a matching model rather than direct funding, so owners need to assess the assigned lender’s final pricing and repayment terms
Best for: med-spas and salons adding high-ticket aesthetic technology.
8. Clara Capital – Best for a Dedicated Relationship-based Lending Partner
Clara Capital takes a relationship-led approach to business funding, with beauty and wellness among the industries served alongside construction, retail, restaurant, medical, and others. The stated goal is to place each client in the funding product that supports maximum growth potential, with dedicated service throughout. The company is headquartered in Syosset, New York, and describes a 20-person team centered on hands-on guidance.
That positioning suits owners who want a person to talk through trade-offs rather than a purely self-serve portal. A mixed-use operator, such as a salon with meaningful retail, may also value a single contact across business lines. The practical decision still comes down to the proposed product and how its repayment schedule fits the business. Owners should use an initial conversation to discuss which product type is proposed, how repayment works across seasons, and what documentation is needed.
Pros
Dedicated, relationship-first service for owners who want guidance on product fit
Multi-industry coverage provides a single point of contact for mixed salon and retail operations
Explicit focus on matching the funding type to the growth stage
Cons
A dedicated contact does not replace product comparison; owners still need to weigh the proposed repayment schedule against their seasonal cash flow
Best for: beauty and wellness owners who prefer a dedicated lending partner over a transactional application.
Frequently Asked Questions
1. What types of financing are available to salon and beauty business owners?
Common options include revenue-based working capital, term loans, equipment financing, business lines of credit, and SBA loans for larger projects. Working capital bridges payroll and inventory gaps. Equipment financing spreads stations, chairs, wash units, and aesthetic devices over their useful life. A revolving line lets you draw, repay, and draw again across seasons. The right mix depends on whether the need is short-term cash flow, a durable asset, or a multi-year expansion.
2. How do revenue-based or percentage-of-sales repayments work for seasonal salons?
With revenue-based funding, repayment is collected as a set percentage of daily or periodic sales instead of a fixed monthly amount. Payments dip when revenue falls and rise when it peaks. Industry discussion of trends in salon capital advances highlights why that flexibility appeals to appointment-based businesses. Smaller payments during a slow period do not necessarily reduce the contracted total repayment obligation. Owners should review how the percentage is calculated, how often it collects, and whether minimum payments or reconciliation provisions apply before deciding whether the structure fits their seasonal sales.
3. How quickly can a salon owner access funding after applying?
Timelines vary by product and file completeness. Advertised timelines in this list include initial approvals in as little as 2 hours, 24 to 48 hour funding decisions, and disbursement in 4 hours or 24-72 hours, all depending on the provider and application. These are different steps. An approval is not cash in the account, so ask what happens next, which documents can delay disbursement, and when funds could be available for your application.
4. What can salon financing be used for: equipment, renovations, hiring, or all three?
It can cover all three when the product fits the purpose. Providers in this list cite styling stations, shampoo bowls, spa beds, laser and aesthetic devices, back-bar and retail inventory, renovations and treatment room additions, hiring and training, marketing, and second locations. Equipment financing is best for defined assets. Working capital and lines suit payroll, product, and marketing. Larger build-outs may suit SBA or higher-ticket pathways.
5. How much can a salon owner borrow, and what revenue do lenders typically require?
Amounts in this list range from $5,000 at the accessible end to $5,000,000 for large-scale projects, with several providers in the middle for single-location needs. Revenue minimums differ. One provider in this guide states $12,500 in monthly revenue and six months in business as minimums. Others weigh appointment revenue, time in business, and cash flow trends. Bring recent bank statements and a clear use of funds to get an accurate answer.
6. Is collateral required to get a salon business loan?
It depends on the product. Some working capital options in this guide require no collateral. Equipment financing typically uses the financed equipment itself as collateral for that transaction. Lines of credit and SBA loans have their own security requirements. If you rent your space or lack heavy fixed assets, focus on no-collateral working capital or equipment-secured options and review any additional security or guarantee terms before signing.
What to Choose if Seasonal Cash Flow Is the Priority
Start with Platform Funding if variable weekly revenue is the core problem and you want revenue-based payments that fall in slow weeks. For a larger project, Shim Capital offers SBA and line-of-credit pathways alongside working capital. Rise Business Funding is worth considering for rapid initial approvals, advertised in as little as 2 hours in some cases, while Direct Fast Funding advertises same-day deployment for single or multi-location needs in some cases. Monera Capital suits defined equipment purchases that benefit from terms up to 60 months. SBG Funding is the choice here for a revolving line with soft pre-qualification that fits an inventory cycle. Consider Pincutt for a laser, IPL, or microneedling system, and Clara Capital if you want a dedicated partner to talk through product fit. For seasonal salons comparing beauty business financing in 2026, match the repayment structure to the way sales arrive, then weigh the total obligation against the cash needed through quieter weeks.
https://www.strategydriven.com/wp-content/uploads/IMG_2384.jpeg10001500StrategyDriven - Sponsored Contenthttps://www.strategydriven.com/wp-content/uploads/SDELogo5-300x70-300x70.pngStrategyDriven - Sponsored Content2026-10-27 10:55:372026-10-27 10:55:088 Best Salon Financing Providers for Managing Seasonal Cash Flow in 2026
A customer questionnaire, a board summary and a lender’s data request can all send a finance team back to the same records: utility bills, fuel logs, purchasing extracts and supplier responses. Those records often sit in different departments, and nobody agrees on who owns the final number.
Carbon accounting software brings that data into one place, and it has become part of how many companies put sustainable business practices into measurable terms.
Bottom line: The right platform depends on what you need to report, who owns the data and how your company buys software. The five platforms below appear in reading order, not ranked order. Each fit label is an editorial judgment based on vendor product and pricing pages reviewed in October 2026, not hands-on testing.
Set Your Selection Criteria First
Before comparing features, agree on four things with the people who will supply and use the data.
Reporting purpose. List the outputs you owe: a supplier questionnaire, a board summary, a lender request or a regulatory disclosure. Note which emissions each must cover.
Scope 1 covers fuel your company burns directly.
Scope 2 covers purchased electricity, steam, heat and cooling.
Scope 3 covers the value chain, including purchased goods, travel and freight, and often requires supplier data.
Data ownership. Name an owner for each source. Facilities may hold utility bills, fleet management holds fuel logs, and purchasing holds vendor spend. This affects user licenses and approval workflows.
Calculation evidence. Ask to trace a reported figure back to its source document, activity quantity and emission factor. An emission factor converts an activity, such as gallons of fuel, into emissions. Check what the audit trail keeps when someone corrects an approved figure.
Integration fit. A general claim of ERP connectivity doesn’t confirm compatibility with your system. Test the relevant connector with your own data during evaluation.
Quick Comparison
Platform
Editorial fit
Published pricing
Main item to verify
Persefoni
Starting a first inventory
Free Pro plan; Advanced by quote
Which features are add-ons
Sweep
Multi-entity programs and supplier data
Request a quote
Package scope and frameworks needed
Watershed
Detailed Scope 3 measurement
Request a proposal
What human review covers
Microsoft Sustainability Manager
Microsoft-centered environments
US12,000 per tenant per month
Scope 3 coverage by tier
Salesforce Net Zero Cloud
Companies already on Salesforce
Growth edition published
Scope 3 coverage by edition
1. Persefoni
Best fit: A company building its first repeatable inventory before committing a budget.
What it offers: Persefoni Pro is a free, self-service tier for measuring a company’s core Scope 1, 2 and 3 footprint.
What to check: Pro is limited to one user. Confirm that the exact output your customer or board needs is available before entering a year of data.
Pricing:Pro is free. Additional users and some features are add-ons on Pro, and the Advanced tier is priced by quote.
2. Sweep
Best fit: Companies managing emissions across several entities, suppliers and reporting frameworks.
What it offers: Sweep, the sustainability intelligence platform, also publishesthis software shortlist for buyers comparing options. Its “Sweep trees” model organizational supply chains, backed by an extensive emission-factor library. Data uploaded once can be reported against CSRD, GRI, ISSB, TCFD and CDP, and the platform supports supplier engagement and science-based target setting.
What to check: Confirm which frameworks and supplier workflows your package includes. A Starter package serves growing businesses alongside enterprise plans.
Pricing: Request a quote based on your entities and scope.
3. Watershed
Best fit: Companies that need category-level Scope 3 results and receive data in inconsistent formats.
What it offers:Watershed advertises transparent calculations and built-in human review, with purpose-built methodologies for all 15 Scope 3 categories. It also offers activity-based measurement for purchased products and materials.
What to check: Ask who performs the human review, what it covers and how much data preparation your team must do. Follow one figure from its source document to the reported result.
Pricing:No public price on the reviewed pages. Request a proposal tied to your entities and categories.
4. Microsoft Sustainability Manager
Best fit: Companies already using Microsoft business applications, with IT capacity to configure the system.
What it offers: Microsoft Sustainability Manager offers two tiers:
Essentials: calculation models for Scopes 1 and 2 and multiple Scope 3 categories.
Premium: adds all of Scope 3 and product carbon footprint management.
A 30-day free trial is available.
What to check:Map your required Scope 3 categories against each tier. Ask which features are in preview and which are generally available.
Pricing: Essentials is US12,000 per tenant per month. These are tenant subscriptions, so budget implementation and partner services separately.
5. Salesforce Net Zero Cloud
Best fit:Companies that already run sales and service on Salesforce.
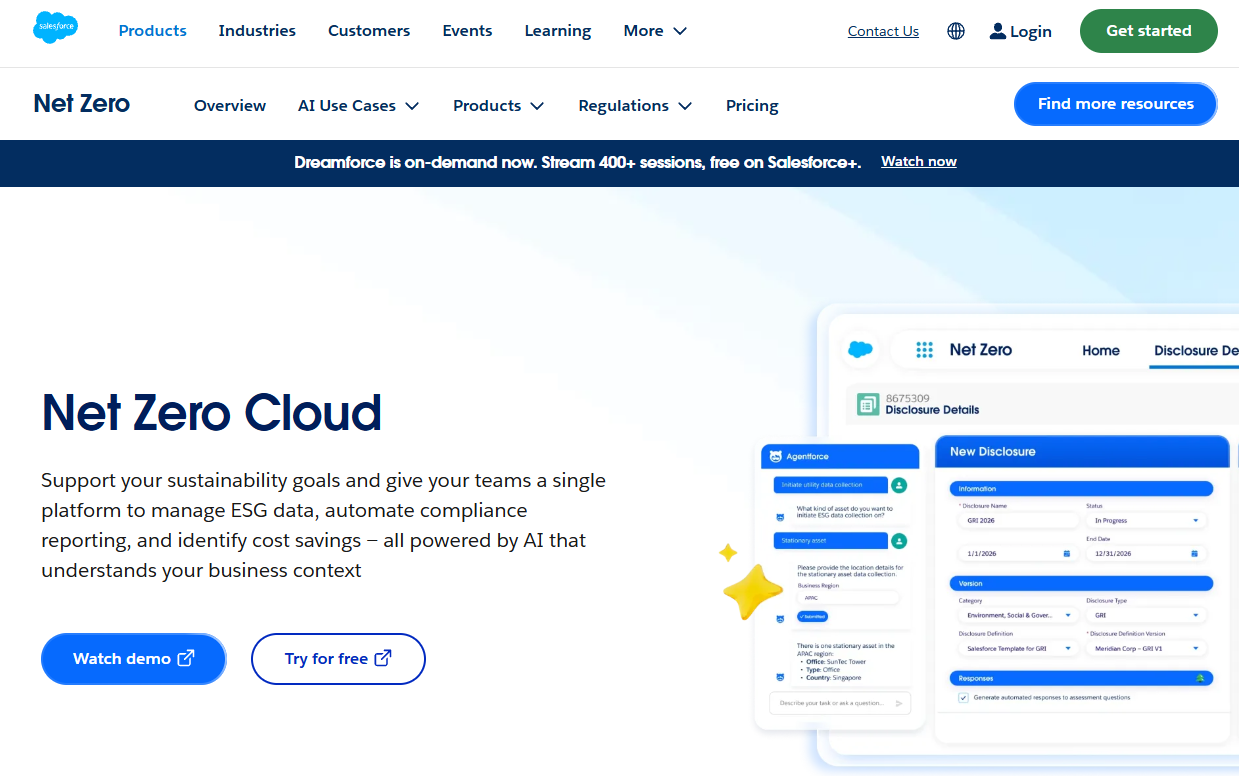
What it offers: Net Zero Cloud tracks Scope 1, 2 and 3 emissions within the Salesforce platform. Its Growth edition adds Scope 3 Hub for spend-based purchased goods, supplier sustainability data and carbon credit management.
What to check: Scope 3 coverage varies by edition. Scope 3 Light covers business travel and freight, while Growth adds waste and purchased goods.
Pricing: The Growth edition is listed at US$210,000 per org per year, billed annually, including one CRM license.
Validate the Shortlist Before Signing
A demo built on a vendor’s sample company may not expose gaps in your own records. Run the same pilot with every finalist.
Run an identical pilot. Give each vendor the same packet: an electricity bill, a fleet fuel record, a monthly purchasing extract and one supplier response. Ask them to:
Attach each document to its activity figure.
Explain the emission factor they chose.
Correct an approved number and show the approval history.
Export the report your customer or board needs.
Compare the full cost. Build a worksheet covering:
The subscription, priced in each vendor’s own unit
Setup and configuration
Integration work for each connector
Advisory support
Additional users and entities
Renewal terms
Data exit, including the format and cost of retrieving records and audit trails
Assign ownership. Name the owner of each data source, the person who approves reported figures, and the administrator who maintains factors and hierarchies.
FAQ
1. What is carbon accounting software?
It collects activity data such as energy bills, fuel use and purchases, applies emission factors, and reports Scope 1, 2 and 3 emissions.
2. Is there free carbon accounting software?
Persefoni offers a free single-user Pro tier. Paid add-ons or upgrades are needed for additional users and some reports.
3. Why is Scope 3 the hardest to measure?
Most Scope 3 data sits with suppliers and customers, so collecting it requires outreach, estimates and consistent methods.
4. Does software make a report audit-ready on its own?
No. Software can organize evidence and audit trails, but external assurance requires an independent reviewer.
Final Thoughts
Start with what you must report and who owns each input, then shortlist platforms whose pricing model matches how your company buys software. Run the same pilot with every finalist, and choose the platform that can trace each figure back to its source.
https://www.strategydriven.com/wp-content/uploads/IMG_2368.jpeg9271500StrategyDriven - Sponsored Contenthttps://www.strategydriven.com/wp-content/uploads/SDELogo5-300x70-300x70.pngStrategyDriven - Sponsored Content2026-10-23 21:09:462026-10-23 21:09:46Best Carbon Accounting Software for US Businesses in 2026
Fourteen minutes. That’s how long the average board member spends with the financial packet before a quarterly meeting, and most of that time goes to the page with the biggest number on it. I’ve watched a treasurer walk eleven people through a balance sheet while nobody noticed that three months of payroll sat in a temporarily restricted fund.
You don’t need a CPA to catch that. You need about six questions and the willingness to ask them out loud. This isn’t about becoming an accountant. It’s about reading your own organization’s numbers well enough to protect the mission, the staff, and your own name on the IRS filing.
Most boards get talked out of asking hard questions because the reports look official. They shouldn’t be. A statement of financial position is a story about what you own, what you owe, and how much of it you’re actually free to spend. That last part is where things go sideways. If your board has reached the point where nobody can confirm that, it’s worth understanding outsourced accounting for nonprofits as a staffing model, because fund accounting under ASC 958 is a specialty, not a general bookkeeping task.
Why nonprofit statements look nothing like a business P&L
A for-profit reads one number: profit. Your organization reports net assets, and the word “net” hides more than it reveals.
Net assets come in two buckets. Without donor restrictions is money you can spend on whatever serves the mission. With donor restrictions is money tied to a purpose or a deadline, and spending it wrong can mean repaying a grant. A healthy-looking surplus can be entirely restricted, which means you have a great year on paper and a cash problem in practice.
That distinction isn’t a formatting quirk your accountant invented. It’s a reporting requirement. The Financial Accounting Standards Board sets the rules that separate the two classes, and the terminology changed in recent years when the old three-class system was simplified. If your statements still show “temporarily restricted” as a separate column, someone is working from an outdated template.
Here’s my honest take: any board member who can read a personal mortgage statement can read these reports. The math isn’t harder. The vocabulary is just unfamiliar, and unfamiliar vocabulary makes people quiet in meetings.
The Six Questions That Expose Almost Everything
Print the packet, grab a pen, and work through these in order. It takes less time than the small talk before the meeting starts.
1. Does cash cover the next 60 days? Compare the bank balance to your average monthly expenses. Under two months is a conversation. Under one month is a crisis you’re finding out about late.
2. How much of the surplus is restricted? Point to the net assets section and make them separate the two buckets out loud.
3. What’s the largest receivable, and how old is it? A big grant invoice sitting unpaid for five months is a cash flow problem wearing a costume.
4. Did any single donor exceed 10 percent of revenue? Concentration risk kills small organizations quietly.
5. Are payroll taxes current? Unpaid payroll tax liabilities are one of the fastest ways a nonprofit gets into serious trouble with the IRS.
6. Who reconciled the bank account last month, and can they prove it? If nobody can answer, your internal controls have a hole.
That’s the whole routine. You’re not auditing. You’re checking whether the story the numbers tell matches the story the executive director just told you.
Red Flags You Can Spot In Under a minute
Some signals don’t need analysis. They need a follow-up question in the meeting.
Revenue is booked when a pledge is made rather than when it’s collectible, so the surplus exists only on paper.
Restricted funds paid for unrestricted expenses, with a “we’ll fix it later” note in the margin.
Deferred revenue missing from a program that takes payment up front for services delivered over months.
The same person writes checks, signs them, and reconciles the account.
Functional expense allocations that have stayed identical for years even though the programs changed.
Segregation of duties is the one I’d fix first, even at a five-person organization. It doesn’t require hiring anyone. It requires the board treasurer opening the bank statement before anyone else does.
A Practical Onboarding Routine for New Board Members
New members nod through their first two meetings and vote on things they don’t understand. Skip that. Ask the executive director for three things before your first vote: the most recent audited financials, the current year budget to actuals, and a five-minute walkthrough of how a donation gets recorded from receipt to bank deposit.
Then do this. Pick one restricted grant at random and trace it from the award letter to the general ledger entry. You’ll learn more in twenty minutes than from any orientation packet. The National Council of Nonprofits publishes plain-language explainers on board financial duties if you want a starting point that isn’t written for accountants.
I’d also push back on the idea that financial literacy is optional for board service. It’s not a nice-to-have skill you pick up over a few years. It’s the job. Fundraising gets the attention because it’s social and visible. Reading the numbers is what keeps the organization alive long enough to spend the money well.
When to Bring In Outside Help
Some situations are beyond what a volunteer treasurer should carry. You’ve outgrown QuickBooks. You have multiple restricted funds and grant compliance reports due in different formats. Your bookkeeper left without documenting anything and the audit is in eight weeks. Your Development team is raising money faster than the back office can record it.
A volunteer CPA on the board can offer opinions, but an independent practitioner handles the work and keeps your board’s oversight role intact. That separation matters more than most people realize, because a board that prepares the numbers can’t independently review them.
You don’t need to know the difference between a modified cash basis and an accrual basis statement to hire well. You need to know what question you’re trying to answer. If that answer is “we can’t tell whether we’re solvent,” hire for the specific problem, ask for a monthly close on a fixed date, and require a written narrative alongside the numbers.
Get one thing right this quarter. Pick the question your board has been avoiding and put it on the agenda with a name next to it. The Association of Fundraising Professionals has long argued that donors and boards alike should expect real financial transparency, and the simplest way to prove you mean it is to ask the uncomfortable question in front of everyone, then write down the answer.
Your organization’s finances are only as clear as the least curious person in the room. Which number has your board been staring past for the last three quarters?
https://www.strategydriven.com/wp-content/uploads/IMG_2365.jpeg10001500StrategyDriven - Sponsored Contenthttps://www.strategydriven.com/wp-content/uploads/SDELogo5-300x70-300x70.pngStrategyDriven - Sponsored Content2026-10-22 17:51:532026-10-22 17:51:53How Nonprofit Boards Can Read a Financial Statement Without a Finance Degree
Picture a Sunday morning in Lisbon. You’ve finally settled into your new life abroad, with a local bank account, a lease you understand and a favorite café around the corner. Then a letter from your bank asks you to confirm whether you’re a U.S. citizen. Suddenly a rule you’ve never heard of is asking for your attention, and it can feel intimidating at first.
If you’re an American living overseas, that moment is more common than you’d think. The good news is that FATCA doesn’t have to be a source of dread. Here’s a friendly, practical look at what it means, and how it fits alongside the rest of your expat money plan.
What FATCA Actually Is
FATCA stands for the Foreign Account Tax Compliance Act. In simple terms, it’s a U.S. law designed to help the IRS see the financial accounts that U.S. taxpayers hold abroad. It works in two directions: foreign financial institutions report certain information about accounts held by U.S. persons, and individual taxpayers with enough foreign assets must report them on their own tax return.
That’s why your overseas bank may ask about your citizenship. They’re not singling you out. They’re following rules that apply to institutions around the world, and answering honestly is part of staying on the right side of the system.
Who Has to Report and When
For individuals, the main FATCA filing is Form 8938, which accompanies your U.S. tax return when your specified foreign financial assets pass certain limits. The IRS sets higher thresholds for people living abroad than for those living in the United States.
According to the IRS, unmarried taxpayers living abroad must file Form 8938 if their foreign financial assets exceed $200,000 on the last day of the tax year or $300,000 at any time during the year, and for married couples filing jointly the limits are $400,000 and $600,000.
Those figures apply to taxpayers who qualify as living abroad, and other filing statuses have their own limits. The IRS notes that failing to file can lead to a $10,000 penalty, with further penalties for continued failure after notification, so it’s worth understanding where you stand.
FATCA Is Not the Only Rule
Many expats confuse FATCA with the FBAR, the Report of Foreign Bank and Financial Accounts. They’re separate requirements with different forms, thresholds and agencies. The FBAR goes to the Treasury’s FinCEN and has its own limit, while Form 8938 is filed with your tax return.
Depending on your situation, you may need to file both, one or neither. It’s one reason a broader view helps. Foreign accounts, income, retirement savings and investments can each trigger different reporting rules, and they all connect.
Where Compliance Fits in Your Bigger Plan
Think of compliance as the foundation of your expat financial plan rather than a separate chore. Everything else you want to do, from saving for retirement to buying property abroad, sits on top of it.
Here’s how it connects to other parts of your strategy:
Taxes: Your annual U.S. return pulls together income, foreign tax credits, exclusions and reporting forms, so accounts and income need to line up
Banking: Choosing accounts and institutions with U.S. reporting in mind can save time and awkward conversations later
Investing: Some foreign investment products come with extra reporting or tax treatment for U.S. persons, so check before you buy
Retirement: Foreign pensions and savings plans may have special reporting rules, so planning ahead avoids surprises
Family and estate planning: Joint accounts, spouses with different citizenships and inheritances can all affect your obligations
When these pieces are coordinated, reporting becomes a routine part of your year rather than a stressful scramble. Keeping FATCA compliance in view all year, instead of only at filing time, is what stops it from derailing the rest of your plan.
Why Staying on Top of It Matters
Penalties are the obvious reason, but they’re not the only ones. Clean, accurate records make everything easier, from applying for a mortgage to selling property or planning a move home.
Staying compliant also gives you peace of mind. Knowing your reporting is up to date means you can focus on enjoying life abroad instead of worrying about a letter in the mail. If you’ve missed filings in the past, the IRS has procedures for catching up, and a qualified professional can explain which one fits your circumstances.
Choosing the Right Support
Expat tax rules are layered, and a mistake on one form can ripple into others. A specialist who works with Americans abroad every day will know the thresholds, forms and deadlines, and can spot issues you might not realize you have.
When you’re comparing providers, a few questions help:
Do they work specifically with U.S. expats, and do they handle both Form 8938 and the FBAR
Who actually prepares and reviews your return
Do they look at your whole financial picture, or only fill in forms
How do they protect your personal and financial information
Is pricing clear before you start, and what does it include
One company in this space is MyExpatTaxes, which focuses on tax services for U.S. expats. Its website explains FATCA, Form 8938 and the related FBAR requirement, and lists services that include do-it-yourself tax filing, professional assistance, FBAR filing, tax planning and support with citizenship renunciation. Whichever provider you consider, get the details of what’s included in writing before you commit.
Common FATCA Mistakes to Avoid
Most problems come from small misunderstandings rather than big oversights. These are the ones expats run into most often:
Assuming the FBAR and Form 8938 are the same thing, when they’re separate filings with different rules
Forgetting accounts held jointly, or accounts that feel too small or too dormant to matter
Overlooking assets beyond bank accounts, such as certain foreign investments or pension products
Guessing at balances or exchange rates instead of keeping clear records
Ignoring a bank’s request for citizenship information, or delaying a filing until a notice arrives
Catching these early is far easier than fixing them later, and if you suspect you’ve missed something, a qualified tax professional can explain your options for getting back on track.
Build a Simple Annual Routine
You don’t need a complicated system to stay on track. A few habits make a big difference:
Keep a running list of every foreign account, including the institution, country, account type and highest balance for the year
Save statements and records in one secure place, so they’re easy to find at tax time
Track exchange rates or note the conversion method you use, since reporting is in U.S. dollars
Review your accounts each year to see if you’ve crossed any thresholds
Mark your filing deadlines in your calendar, including extensions if you’re abroad
A little organization throughout the year makes filing far less painful.
Conclusion
FATCA compliance is best seen as one part of a bigger expat financial picture rather than a standalone burden. By understanding what the law requires, knowing how your foreign accounts fit alongside taxes, banking, investing and retirement planning, and keeping simple records throughout the year, you can stay organized and avoid unpleasant surprises. If anything feels unclear, ask a specialist who works with Americans abroad. This article is general information, not tax advice, but with a calm approach and the right support, your reporting can fade into the background while you enjoy the life you’ve built overseas.
https://www.strategydriven.com/wp-content/uploads/IMG_2322.jpeg10011500StrategyDriven - Sponsored Contenthttps://www.strategydriven.com/wp-content/uploads/SDELogo5-300x70-300x70.pngStrategyDriven - Sponsored Content2026-10-05 16:31:512026-10-06 09:30:35How FATCA Compliance Fits Into a Broader Expat Financial Strategy
 A VETERAN OWNED SMALL BUSINESS |
 Business Programs